German Green Steel and Power Limited
Sector: Iron & Steel Manufacturing (Secondary Steel — TMT Bars, MS Billets, Sponge Iron)
1. Overview
German Green Steel and Power Limited are a vertically integrated iron and steel manufacturer based in Gujarat, India, with a principal focus on TMT Bars. Originally incorporated in 2008 as Haq Enterprises Private Limited, the Company underwent successive name changes before adopting its current identity in 2024. It operates two manufacturing facilities in Gujarat — the Samakhiyali Facility (fully vertically integrated, from Sponge Iron through to finished TMT Bars) and the Viramgam Facility, run through its Material Subsidiary, German TMT Private Limited.
The Company's product portfolio spans Sponge Iron, MS Billets and TMT Bars (8mm–40mm, grades Fe500 to Fe550D CRS), with a growing push into value-added products such as epoxy-coated and corrosion-resistant TMT bars. Its "German TMT" brand has built strong recognition in Gujarat, supported by ISO 9001:2015, ISO 45001:2018 and ISO 14001:2015 certifications and a Green Steel rating (4-star for the Company, 5-star — the highest tier — for its Material Subsidiary) from the National Institute of Secondary Steel Technology.
Financially, the Company has shown a consistent growth trajectory: revenue from operations grew at a 21.91% CAGR from ₹1,129.78 Cr in FY2024 to ₹1,678.98 Cr in FY2026, while EBITDA grew at a 45.07% CAGR over the same period, with EBITDA margin expanding from 7.02% to 9.94%. Geographically, the business remains heavily concentrated in Gujarat (97.74% of FY2026 revenue), with early expansion into Punjab, Rajasthan, Maharashtra and Karnataka. Within the competitive landscape, the Company benchmarks against listed peers such as Beekay Steel Industries, Gallant Ispat, Kamdhenu, MSP Steel & Power and VMS TMT, and reported the highest EBITDA margin, PAT margin and RONW among these peers in FY2026.
2. Business Model and Revenue Streams
Revenue by Customer Channel
The Company sells on a business-to-business basis through three channels — distributors, dealers and direct institutional customers (corporates in roadways, engineering services, thermal plants and real estate). Distributors operate under formal agreements with pre-defined discount and credit terms; dealers largely transact without formal agreements and at smaller volumes. (Revenue - ₹ Cr)
| Channel | FY2026 | % | FY2024 | % |
|---|---|---|---|---|
| Distributors | 630.76 | 37.57% | 598.16 | 52.94% |
| Dealers | 350.66 | 20.89% | 36.44 | 3.23% |
| Institutional Customers | 697.33 | 41.53% | 495.18 | 43.82% |
The mix has shifted meaningfully over three years — institutional and dealer contribution has risen while direct distributor share has declined, reflecting the Company's push toward direct institutional relationships and dealer-network expansion (dealer count grew from 73 in FY2024 to 148 in FY2026).
Client Concentration
The Company derives a majority of revenue from a concentrated customer base: its top 10 customers contributed 50.62% of FY2026 revenue, with the single largest customer alone contributing 10.67%. This concentration is flagged as a material risk, though 7 of the top 10 customers have relationships exceeding three years, indicating some retention strength despite the absence of long-term supply contracts (sales are largely purchase-order driven).
Geographic Footprint
Revenue remains overwhelmingly Gujarat-centric:
| Region | FY2026 (%) | FY2025 (%) | FY2024 (%) |
|---|---|---|---|
| Gujarat | 97.74% | 99.77% | 98.59% |
| Punjab | 0.52% | 0.02% | 0.06% |
| Rajasthan | 0.19% | 0.09% | 0.49% |
| Maharashtra | 0.14% | 0.05% | — |
| Karnataka | 0.13% | — | — |
The Company has articulated plans to expand into Rajasthan, Maharashtra and Madhya Pradesh, and has entered its first contract manufacturing arrangement with JSW One Distribution Limited (three-year Manufacturing Partner Agreement effective April 2025) to manufacture products under JODL's brand at the Samakhiyali Facility.
3. Products and Service Portfolio
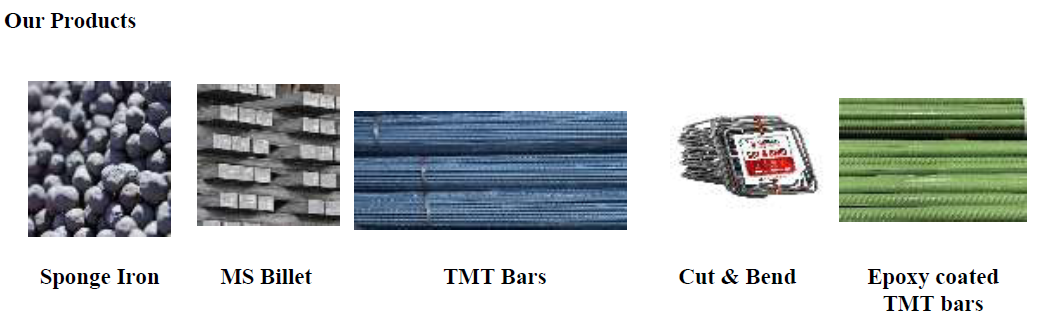
Product-wise Revenue Contribution (FY2026)
| Product | Revenue (₹ Cr) | % of Revenue |
|---|---|---|
| TMT Bars | 1,321.96 | 78.74% |
| MS Billets | 101.16 | 6.02% |
| Sponge Iron | 31.10 | 1.85% |
| Others (scrap, by-products) | 224.53 | 13.38% |
TMT Bars remain the dominant revenue driver, with contribution rising from 63.13% in FY2024 to 78.74% in FY2026, while MS Billets' share has correspondingly declined — consistent with the Company's strategy of moving up the value chain from intermediate to finished products.
Capacity and Utilization (Combined, FY2026)
| Product | Installed Capacity (MTPA) | Capacity Utilization FY2026 | FY2025 | FY2024 |
|---|---|---|---|---|
| Sponge Iron | 66,000 | 95.21% | 99.32% | 98.08% |
| MS Billets | 3,57,060 | 79.44% | 83.43% | 80.66% |
| TMT Bars | 3,01,950 | 87.79% | 72.19% | 75.29% |
Utilization levels are healthy across the portfolio, particularly for Sponge Iron, which has consistently run near full capacity — a key rationale behind the Company's planned capacity expansion (Sponge Iron to ~1,48,500 MTPA, MS Billets to 4,12,500 TPA, TMT Bars to 346,500 MTPA at the Samakhiyali Facility).
4. Key Business Strengths
- Vertically integrated manufacturing at the Samakhiyali Facility, spanning Sponge Iron through finished TMT Bars, supported by a 20 MW captive power plant (16 MW coal-based + 4 MW waste heat recovery) plus hybrid wind-solar capacity, with ~75.44% of FY2026 energy requirements met captively.
- Strategic port proximity — the Samakhiyali Facility sits roughly 105 km from Mundra and 50 km from Kandla, easing raw material imports.
- Established "German TMT" brand in Gujarat, backed by thermex quenching technology, multiple ISO certifications and a top-tier 5-star Green Steel rating at the Material Subsidiary.
- Experienced, hands-on Promoter group — combined 36 and 31 years of industry experience for the Chairman and Managing Director respectively, with family roots in the steel business dating to 1976.
- High and improving capacity utilization, particularly in Sponge Iron (95%+), underpinning the case for the Fresh Issue-funded capacity expansion.
5. Future Growth Strategy
- Capacity expansion — more than doubling Sponge Iron, MS Billets and TMT Bar capacity at Samakhiyali, funded substantially by the ₹226.33 Cr Net Proceeds allocation for the Project.
- Renewable energy scale-up — commissioning an additional 25.20 MW hybrid wind-solar plant in Bharuch to further cut grid dependency and operating costs.
- Operational efficiency initiatives — a new 288 TPD shredder unit to improve scrap-to-furnace feed efficiency, and expanded waste-heat recovery to reduce coal consumption.
- Geographic diversification — extending the distributor/dealer network into Rajasthan, Maharashtra and Madhya Pradesh to reduce Gujarat concentration.
- Foray into contract manufacturing, evidenced by the JODL partnership, to improve capacity utilization and diversify the customer base beyond direct sales.
- Value-added product mix shift — increasing focus on stainless steel round bars, cut-and-bend bars and corrosion-resistant/epoxy-coated TMT bars, alongside new use cases such as ash-brick production from fly ash by-product.

Delete Comment?
Are you sure you want to delete this comment? This action cannot be undone.
Discussion
Join the discussion!
Log In to CommentNo comments yet. Be the first to share your thoughts!