Manika Plastech Limited
1. Overview
Manika Plastech Limited is a design-led, precision engineered rigid polymer packaging (RPP) manufacturing company operating in the Indian rigid plastic packaging sector, catering to critical end-use industries including energy storage, automotive, dairy and edible food products, paints, lubricants, agrochemicals and construction chemicals. The Company was originally incorporated in 1996 as Manika Moulds Private Limited in Maharashtra, subsequently relocating its registered office to Dadra & Nagar Haveli in 2014, and converting into a public limited company in December 2024.
The Company operates seven Operating Facilities across India — comprising six Manufacturing Facilities located at Dehradun (Uttarakhand), Hosur (Tamil Nadu), Panipat (Haryana), Una (Himachal Pradesh) and Dadra, together with one dedicated Painting Facility at Hosur for automotive components. Aggregate manufacturing footprint spans over 51,000 square metres with an aggregate installed capacity of 29,200 MTPA (as of the RHP date), targeted to rise to 38,000 MTPA post-IPO capital deployment. As per the Technopak Report, the Company is one of the top three players in India for recycled polymers / post-consumer recycled processing output during FY2024–26.
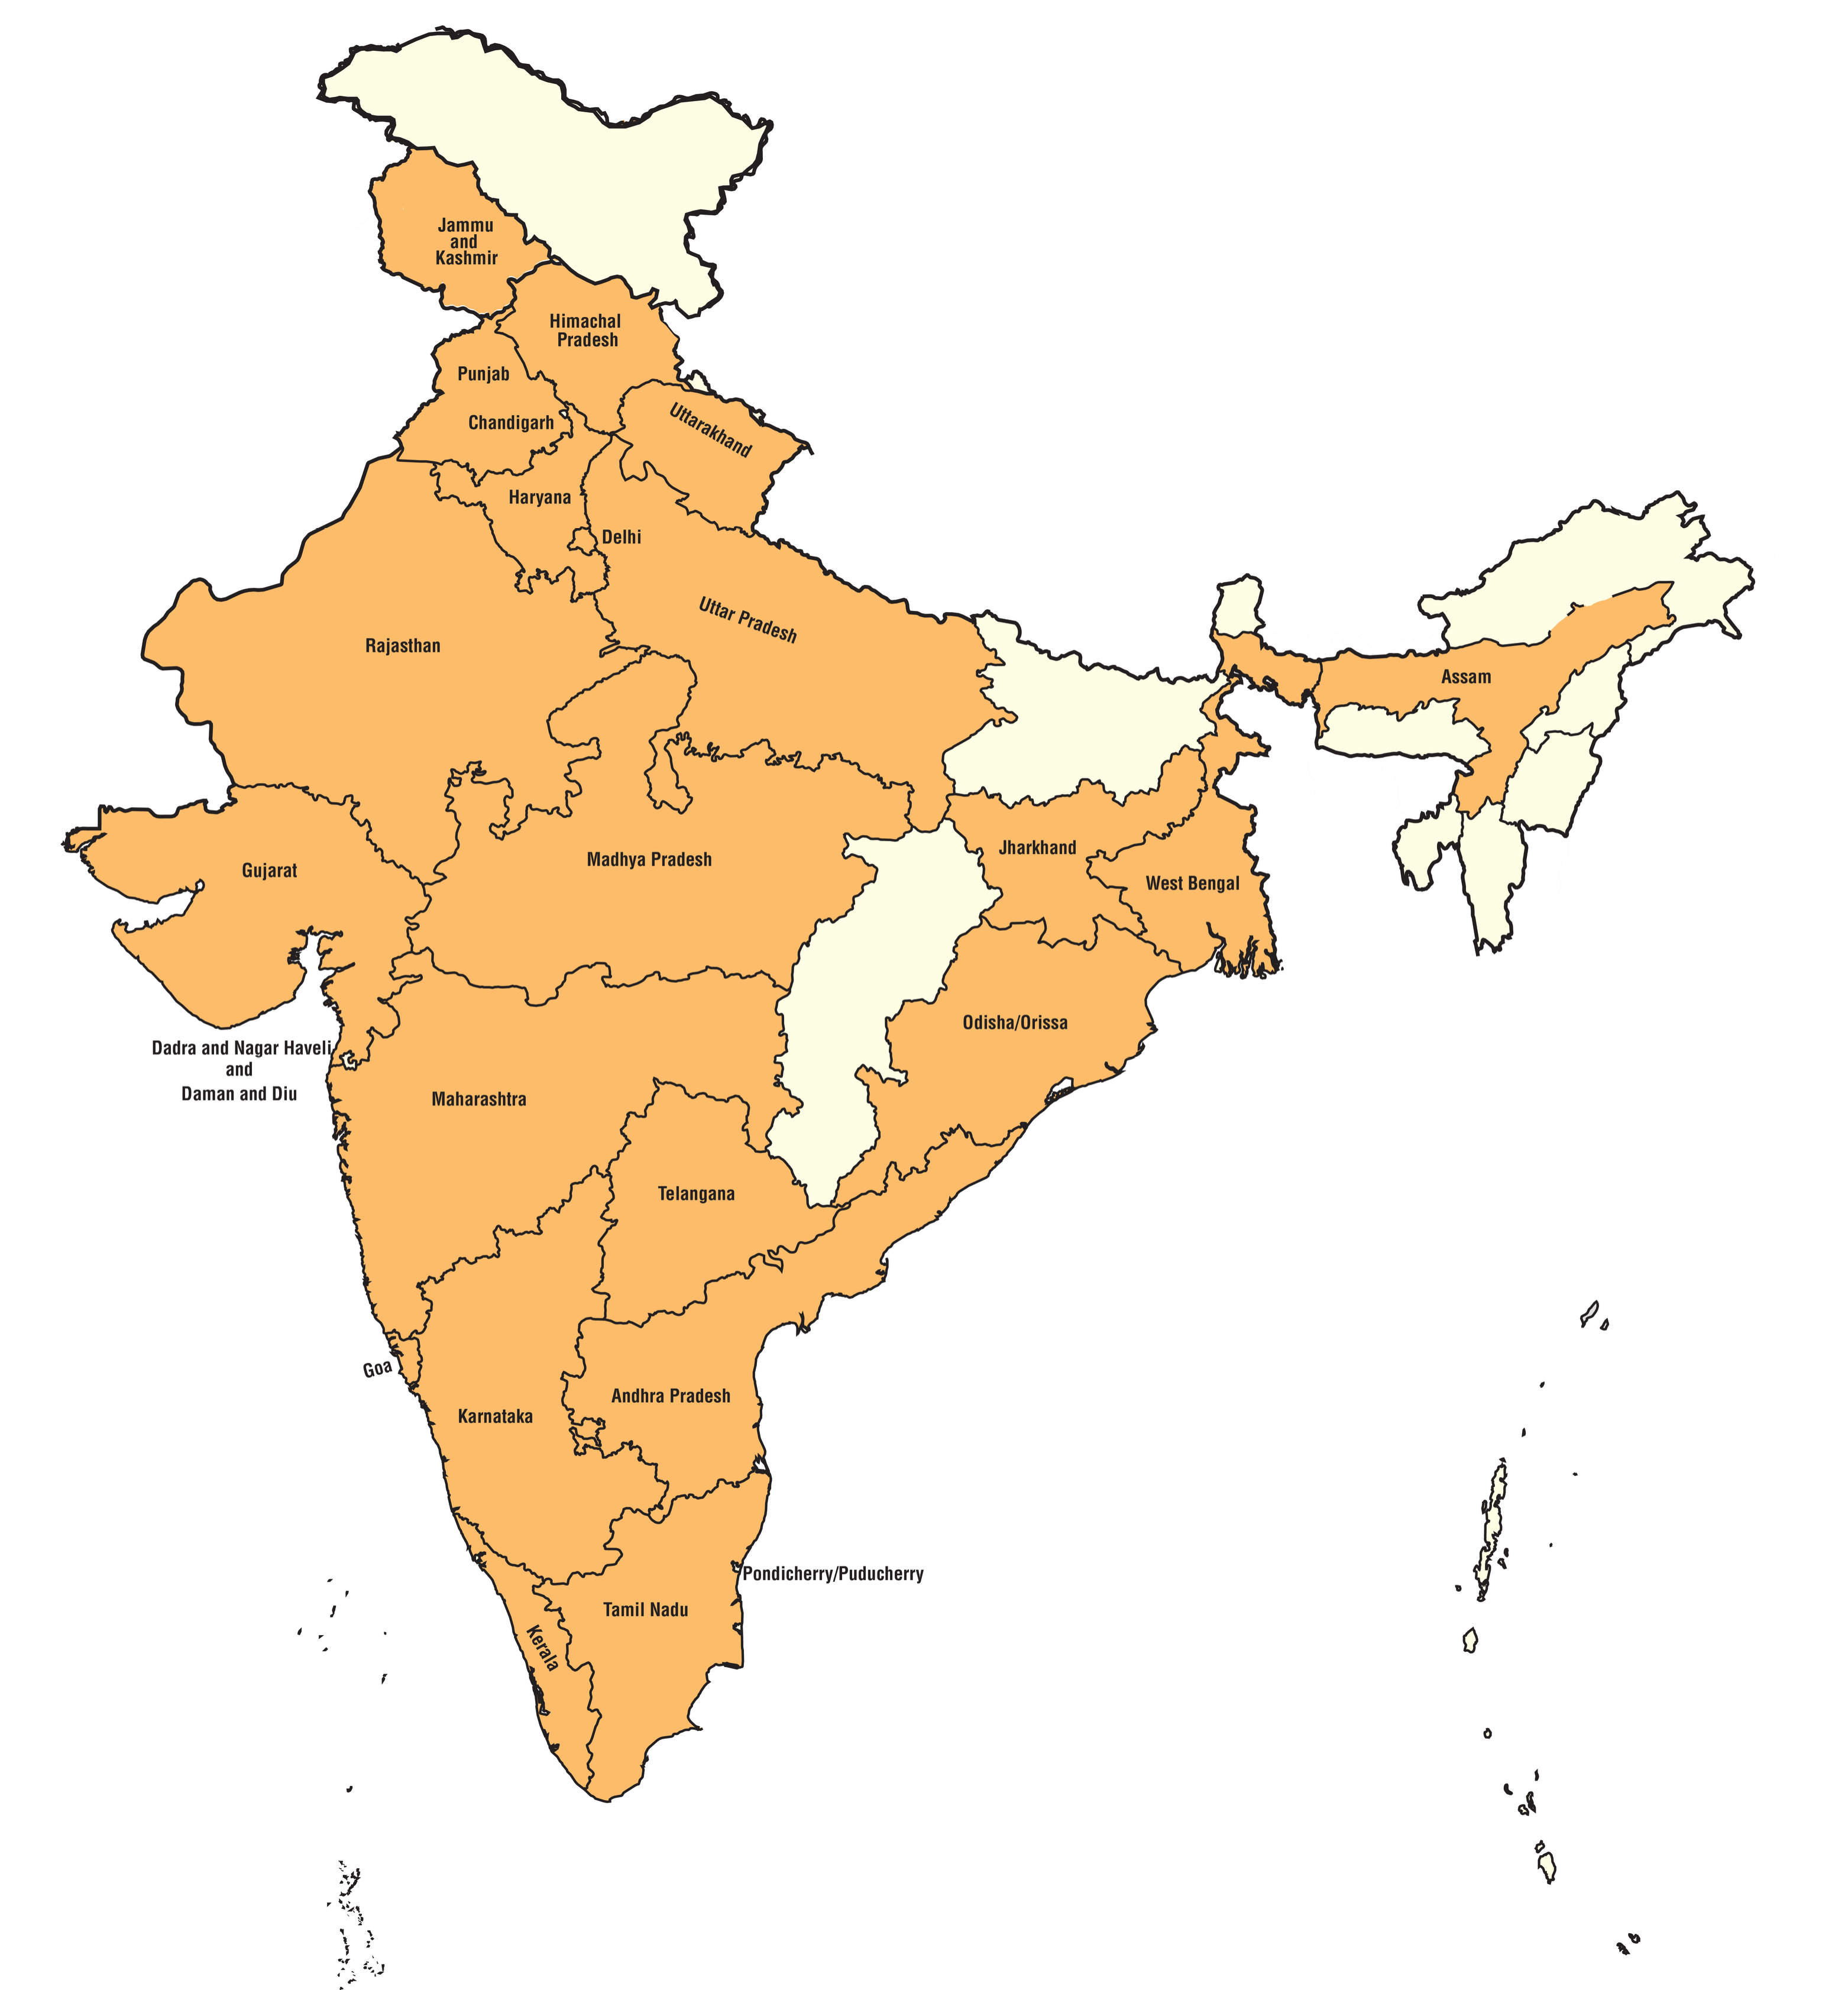
The Company services a diversified base of 168–242 customers across 24 states/UTs, with a long-tenure top-20 customer cohort averaging over 10 years of association. Credit rating stands at CARE BBB+; Positive (May 2026) with a short-term rating of CARE A2.
2. Business Model and Revenue Streams
Revenue by Product Category (Consolidated) (₹ Cr)
| Category | Q1FY27 | % | FY26 | % | FY25 | % | FY24 | % |
|---|---|---|---|---|---|---|---|---|
| Battery Casings | 88.33 | 54.38% | 246.49 | 56.54% | 266.50 | 65.56% | 242.64 | 67.26% |
| Pails & Thinwall Containers | 45.81 | 28.20% | 133.02 | 30.51% | 112.83 | 27.76% | 84.09 | 23.31% |
| Painting Facility | 7.25 | 4.46% | 13.87 | 3.18% | 2.49 | 0.61% | 0.06 | 0.02% |
| Other Operating Revenue | 21.06 | 12.96% | 42.60 | 9.77% | 24.69 | 6.07% | 33.98 | 9.41% |
| Revenue from Ops | 162.45 | 100.00% | 435.98 | 100.00% | 406.50 | 100.00% | 360.77 | 100.00% |
Revenue by Geography (FY26)
| Geography | FY26 (₹ Cr) | FY26 % | FY25 % | FY24 % |
|---|---|---|---|---|
| Northern India | 232.41 | 53.31% | 57.66% | 49.41% |
| Southern India | 124.03 | 28.45% | 25.46% | 30.67% |
| Western India | 61.69 | 14.15% | 13.77% | 17.88% |
| Central India | 5.88 | 1.35% | 1.07% | 0.04% |
| Exports | 10.31 | 2.37% | 1.68% | 1.76% |
| Eastern India | 1.49 | 0.34% | 0.32% | 0.23% |
Business Model Attributes
- Order-driven B2B model: Customers typically place orders based on internal requirements — no long-term binding supply agreements with most key customers; 31.30% (Q1FY27) to 43.75% revenue historically comes from customers associated for more than a decade.
- Customer concentration: Top 5 customers accounted for 58%–69% of operating revenue during Q1FY27 and preceding three Fiscals; Top 10 customers contributed 73%–79%.
- Repeat business intensity: 93%–98% of revenue from operations came from repeat customers across the review periods, reflecting entrenched customer relationships.
- Location-anchored strategy: Facilities and warehouses are set up in proximity to key customer plants — e.g., Panipat facility is 1 km from Grasim Industries; Hosur 3 km from Kansai Nerolac; Una 5–6 km from Luminous Power Technologies and Livguard Energy Technologies.
- Domestic-heavy revenue mix: Exports contribute only ~2.4% of revenue; primary export destinations include Nepal, Sri Lanka, South Africa, Bangladesh, Philippines, Oman, Italy and Zimbabwe.
- Raw material dependence on PPCP: Primary raw material is polypropylene co-polymer (PPCP), sourced from ExxonMobil Chemicals Asia Pacific, Haldia Petrochemicals, Borouge Pte Ltd and other major suppliers; top 5 suppliers accounted for ~66.80% of purchases (FY26).
- Related party dividend flows: The Promoter Selling Shareholder VRIDAA Holding Trust received dividends of ₹3.69 Crore (Q1FY27), nil (FY26), ₹2.03 Crore (FY25) and ₹1.84 Crore (FY24).
3. Products and Service Portfolio
Product Segments and Applications
| Main Product | Key Model / Range | End-Use Industry |
|---|---|---|
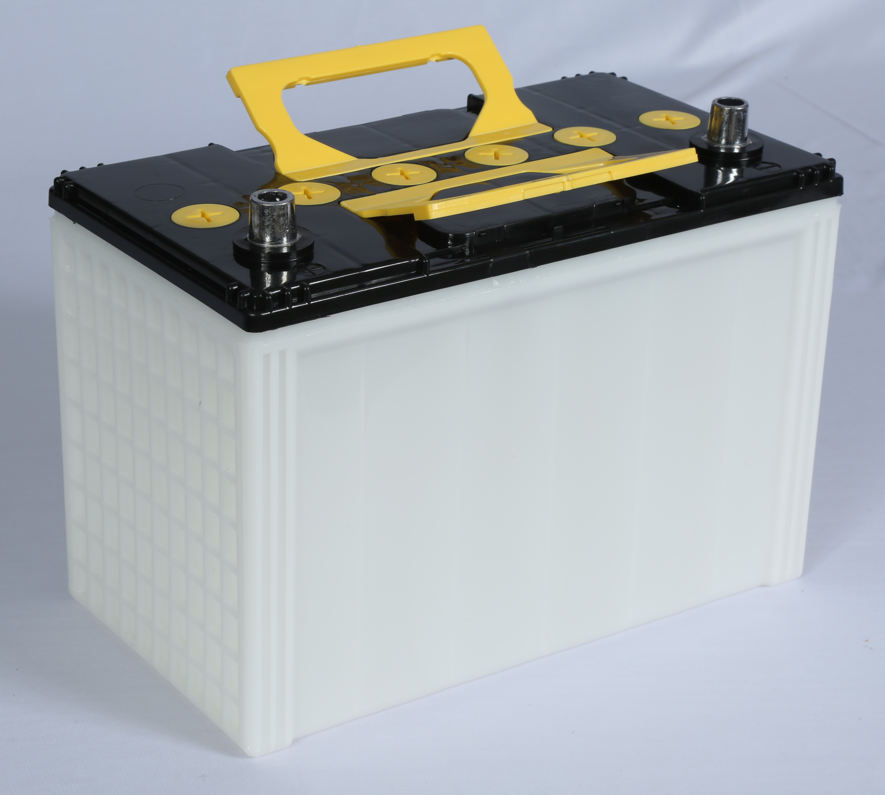
| Battery Casings | 2.5 AH to 9 AH | Automobiles |
| NS 40 to N 200, DIN 44 to DIN 88, B 20 to D 31 | Automobiles | |
| Inverter series (150 Jumbo, 200 Jumbo, IT 500, STT 500, IT 700, 36 G) | Renewable energy / Power back-up | |
| Railways series (10V/75AH–90AH and 6V/120AH) | Railways | |
| 2V/400 AH to 2V/800 AH | Renewable energy | |
| 7MG and 8MG | Forklift | |
| Maintenance-free series (7 AH to 200 AH) | IT data centres, server rooms | |
| Pails | 250 grams to 20 kg | Paints, lubricants, fertiliser, construction chemicals |
| 250 ml to 25 litres | Paints, lubricants, fertiliser, construction chemicals | |
| Thinwall Packaging Containers | 100 ml round IML to 1,000 ml round; Square IML 750–1,000 ml; Rectangle 750 ml; Hinge 600 / 750 ml | FMCG / Dairy / Edible Food |
SKU and Mould Portfolio (Q1FY27 cumulative)
- Battery casings: over 2,700 SKUs sold; PPCP and ABS raw materials
- Pails: over 2,900 SKUs sold; PPCP
- Thinwall containers: over 1,000 SKUs sold; PPCP
- Total moulds owned: over 800 moulds (RHP text also references 870 moulds in newer disclosures)
- Registered designs: 30 designs for battery casings and battery lids registered under the Designs Act, 2000
Facility-wise Product Manufacturing Mapping
| Unit Location | Products Manufactured | Key Customers Served |
|---|---|---|
| Dadra (DNH) | Pails & Thinwall containers | Vadilal Industries Limited and other dairy/food manufacturers |
| Dehradun (Uttarakhand) | Battery casings | Livguard Energy Technologies, Luminous Power Technologies, Genus Innovation, HSD Batteries (India) |
| Hosur (Tamil Nadu) — Manufacturing | Battery casings, Pails & Thinwall containers, Automotive components | Luminous Power Technologies, Kansai Nerolac Paints, JSW Paints, Sakthi Accumulators, Surya Batteries, Zunax Energy Products |
| Hosur (Tamil Nadu) — Painting | Painting of automotive components | Ultraviolette Automotive, TVS Motor Company, other auto-component / commercial EV OEMs |
| Panipat (Haryana) | Pails & Thinwall containers | Grasim Industries Limited |
| Una (Himachal Pradesh) | Battery casings, Pails & Thinwall containers | Livguard Energy Technologies, Luminous Power Technologies, Kansai Nerolac Paints |
Manufacturing Metrics
- Aggregate installed capacity: 29,200 MTPA (across 6 Manufacturing Facilities); target post-IPO capex 38,000 MTPA (+30% capacity)
- Capacity utilisation: improved from ~75% in FY24 to ~80% in Q1FY27
- Production volume: grew at 6.27% CAGR from 18,614 MT in FY24 to 21,023 MT in FY26
- Machinery base: 93 injection moulding machines, of which 72 (77%) are energy-efficient SERVO-type motors
- Solar power usage: 18.04%–26.61% of total power consumption during Q1FY27 and prior three Fiscals came from solar (Dadra and Hosur)
- Recycled polymer content: constituted 13%–30% of total polymer consumption during Q1FY27
Quality Certifications
- ISO 9001:2015 (Quality Management)
- ISO 14001:2015 (Environment Management)
- ISO 45001:2018 (Occupational Health & Safety Management)
- IATF 16949 (Automotive Quality — Hosur only)
4. Key Business Strengths
- Customer proximity and operational flexibility: Manufacturing facilities and warehouses located within 1–26 km of anchor customer plants, enabling reduced logistics costs, shorter lead times, and integration into customer production workflows.
- High entry barriers and customer stickiness: New customer approvals typically require ~1-year audit cycles; high switching costs, tailored solutions and IP considerations create structural exit barriers for customers, translating into 2+ decade average relationships with the top 20 clientele.
- Integrated in-house design and development: 29 full-time design personnel at Corporate Office and Manufacturing Facilities enable full-cycle capability from design → mould design → manufacturing → labelling → delivery; 30 registered designs under Designs Act, 2000.
- De-risked, multi-industry product portfolio: 6,773 products across battery casings, pails and thinwall containers spanning automobiles, energy storage, railways, paints, lubricants, agrochemicals, construction chemicals and FMCG — reducing dependency on any single end-industry.
- Multi-standard compliance: Battery casings compliant with Japanese Industrial Standards (JIS) and Deutsches Institut Für Normung (DIN) enable direct integration into international customer filling and labelling lines.
- Sustainability and ESG orientation: One of India's top three players in recycled polymer/PCR processing; solar power at multiple facilities; rainwater harvesting at Una and Hosur; regulatory tailwind from GoI's mandate of 30% recycled content by FY2025-26 rising to 60% by FY2028-29 in Category I rigid plastic packaging.
- Long-tenure promoter leadership: Individual Promoters — Nikunj, Munjal, Mihir and Pratik Kapadia — each carry 20+ years' RPP industry experience, spanning first and second generations of the family business.
- Diversified supplier base: Raw material sourcing from ExxonMobil Chemicals Asia Pacific, Haldia Petrochemicals, Borouge Pte Ltd and others; 16.49% raw material via imports supports commercial-terms flexibility and geopolitical-risk diversification.
- Improving credit profile and deleveraging trajectory: Debt-to-Equity ratio improved from 0.86 in FY24 to 0.60 in FY26; credit rating outlook revised from Stable (Dec 2024) to Positive (Dec 2025 / May 2026).
- Enterprise systems and process rigour: SAP ECC6 deployed across all Operating Facilities; automatic camera-based visual inspection for pails & thinwall containers; high-voltage leak testing for battery casings.
5. Future Growth Strategy
- Capacity expansion via IPO proceeds: Deployment of ₹54.93 Crore from Net Proceeds towards purchase of plant and machinery, targeted to raise installed capacity from 29,200 MTPA to 38,000 MTPA (+30%) at existing Manufacturing Facilities.
- Foray into ISBM technology and new product categories: Investment in Injection Stretch Blow Moulding (ISBM) machines (sourced from Nissei ASB Machine Group) to manufacture PET bottles and jars for water, juices, edible oils, dairy, personal care, cosmetics and pharmaceutical applications — expanding Total Addressable Market beyond current end-industries.
- Southern region geographic expansion: Exploring a new manufacturing facility in southern India to cater to existing customer requirements and onboard new customers.
- Debt reduction and financial deleveraging: Deployment of ₹15.00 Crore from Net Proceeds towards repayment/pre-payment of borrowings; targeted improvement in Debt/Equity ratio and DSCR.
- Vertical integration in automotive Hosur cluster: Adjoining leased land at Painting Facility to expand automotive component manufacturing and painting, leveraging existing OEM relationships (TVS Motor, Ultraviolette) at Hosur — one of India's key automotive manufacturing hubs.
- Expansion of exports footprint: Building on existing exports to Nepal, Sri Lanka, South Africa, Bangladesh, Philippines, Oman, Italy and Zimbabwe; industry export CAGR of 8.42% (CY2019–CY2025) offers structural tailwind.
- Enhanced ESG and circularity positioning: Increasing recycled polymer share in raw material inputs; group-captive renewable power sourcing under evaluation; direct alignment with GoI PCR mandates rising to 60% by FY2028-29.
- Existing-customer wallet-share expansion: New product development for existing customers (e.g., IT-700 battery casing; N-150 sliding-handle redesign) to expand share of business without incremental customer acquisition cost.
- New product development pipeline: Additional thinwall containers and expanded product SKUs under current categories; on-request customised designs to convert prospects and deepen category penetration.

Delete Comment?
Are you sure you want to delete this comment? This action cannot be undone.
Discussion
Join the discussion!
Log In to CommentNo comments yet. Be the first to share your thoughts!