Index
Index
General IPO · Part 6 of 12
Rohan, a salaried investor in Pune, applies for an IPO priced at ₹140–148 per share. He ticks "cut-off", bids for one lot of 100 shares, and his bank blocks ₹14,800. Three days later the company announces a single issue price. Who decided that number, and why did it land where it did?
The answer is book building, the pricing method behind almost every mainboard IPO in India. The company does not announce a fixed price. It publishes a range and lets bids decide where the price lands within it. Once you understand the mechanics, three things make sense:
- Your money is blocked at the top of the band.
- Bidding low never wins you a discount.
- A book that is 50 times oversubscribed still does not guarantee a strong listing.
(Rohan is an illustrative investor used throughout this article.)
Practical Tips
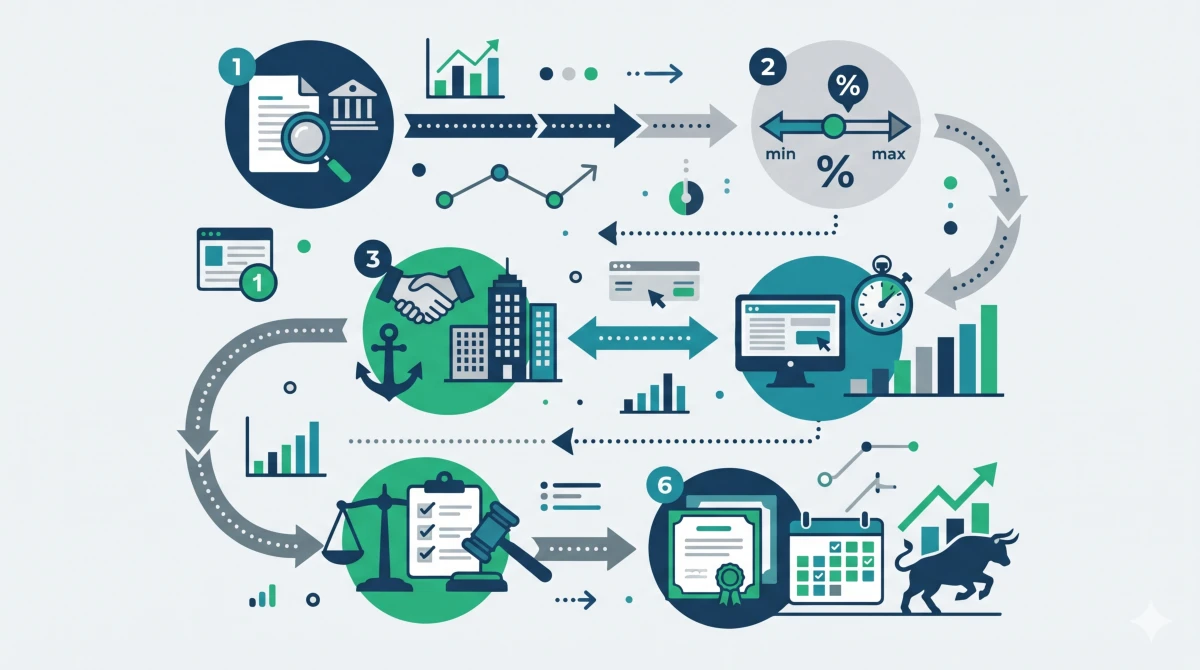
The Six Stages of Book Building
A book-built IPO moves through a fixed sequence. The table shows each stage and when it happens relative to the issue.
| Stage | When | What Happens |
|---|---|---|
| 1. DRHP filing | Months before the issue | Draft offer document filed with SEBI for observations |
| 2. RHP and price band | At least 2 working days before opening | Price band announced; cap can be no more than 120% of the floor and no less than 105% |
| 3. Anchor book | 1 working day before opening | Large institutions are allotted shares at a single price within the band |
| 4. Bidding period | Minimum 3, maximum 10 working days | Investors bid through ASBA or UPI; exchanges show live category-wise demand |
| 5. Price fixing | After bidding closes | Issuer and BRLMs set the issue price from the book |
| 6. Allotment and listing | By T+3 working days | Basis of allotment finalised, funds unblocked, shares listed |
If the price band is revised while the issue is open, the bidding period must be extended by at least three working days, with the total bidding period capped at ten working days. Revisions are rare in strong markets. When they do happen, they usually signal that the original band misjudged demand.
Who Gets What: The Category Quotas
The book is not one pool. SEBI splits it into investor categories, and each category's demand is recorded separately. Most IPOs are issued under Regulation 6(1), which applies to companies meeting profitability track-record criteria. Loss-making companies list under Regulation 6(2) and must use a structure weighted towards institutions.
| Category | Regulation 6(1) | Regulation 6(2) |
|---|---|---|
| QIBs (incl. anchors) | Not more than 50% | At least 75% |
| Non-Institutional (NII/HNI) | At least 15% | Not more than 15% |
| Retail (up to ₹2 lakh) | At least 35% | Not more than 10% |
The retail quota stayed unchanged in 2025. SEBI had proposed cutting it for very large issues, but the plan to reduce retail allocation from 35% to 25% for IPOs above ₹5,000 crore was withdrawn at its September 2025 board meeting.
The NII portion is split further: one-third goes to applications between ₹2 lakh and ₹10 lakh, and two-thirds to applications above ₹10 lakh.
The Anchor Book: The First Signal
Anchor investors bid a day before the public issue opens. They are large institutions applying for at least ₹10 crore each, and they can be allotted up to 60% of the QIB portion. Their allocation is announced publicly, so the anchor list is the first real evidence of institutional appetite.
SEBI widened this book in late 2025. 40% of the anchor portion is now reserved for specific domestic institutions: 33.33% for mutual funds and 6.67% for life insurance companies and pension funds. If the insurer and pension fund reservation goes unsubscribed, it is reallocated to mutual funds.
Anchors cannot exit immediately. Half their shares are locked in for 30 days from allotment and the rest for 90 days. A strong anchor list from long-only funds therefore carries more weight than one dominated by unfamiliar names.
How the Final Price Is Fixed
During bidding, every bid is recorded against a price. Demand is cumulative: a bid at ₹148 also counts as demand at ₹146, ₹144 and every lower price. Cut-off bids are treated as bids at the cap. The illustrative book below shows how this works for an issue offering 10 lakh shares to the public.
| Price (₹) | Cumulative Shares Bid | Times Covered |
|---|---|---|
| 148 (cap) | 1.8 crore | 18.0x |
| 146 | 1.9 crore | 19.0x |
| 144 | 2.0 crore | 20.0x |
| 142 | 2.05 crore | 20.5x |
| 140 (floor) | 2.1 crore | 21.0x |
Illustrative data, not from a real IPO.
The issue is comfortably covered even at the cap, so the issuer and lead managers fix the price at ₹148. They are allowed to pick a lower price within the band to leave something on the table for investors, but in an oversubscribed book this rarely happens. Bids made below the final price are simply rejected.
That is why Rohan's ₹14,800 was blocked at the cap. As a cut-off bidder, his application stays valid at whatever final price is chosen.
Practical Tips
What a Strong Book Tells You, and What It Doesn't
A full book shows that investors were willing to pay the issue price during the bidding window. It does not show what the market will pay on listing day. Two large 2024 IPOs illustrate the gap.
| IPO | Price Band | Issue Price | Book Signal | Listing |
|---|---|---|---|---|
| Bajaj Housing Finance (Sep 2024) | ₹66–70 | ₹70 | Heavy demand across every category | ₹150 (+114%) |
| Hyundai Motor India (Oct 2024) | ₹1,865–1,960 | ₹1,960 | QIB-led; retail portion undersubscribed | Below issue price |
Both issues were priced at the cap. The difference showed up in which categories carried the book. Hyundai's ₹27,859 crore IPO drew retail bids worth only 0.4 times the retail quota. Institutions filled the book, but broad public demand was missing. Bajaj Housing had demand across every category, and the listing reflected it.
The book tells you what institutions were willing to pay, not what the market will pay on listing day.
What This Means for Your Bid
Use the book-building timeline as a checklist:
- Before the issue opens: read the anchor list and note which funds took part.
- During bidding: track category-wise subscription rather than the headline total. A QIB-only book is a weaker signal than a broad one.
- When you apply: bid at cut-off if you are a retail investor, and keep the cap amount available in your account.
- After allotment: remember that heavy oversubscription means a lottery, not a guaranteed lot.
Rohan's issue closed with the retail portion subscribed 18 times and was priced at ₹148. Retail allotment was done by lottery for the minimum lot, and Rohan was not selected. His ₹14,800 was unblocked within the T+3 timeline. He lost nothing except the chance, which is the most common retail outcome in a hot IPO.
KEY TAKEAWAYS
- Book building lets demand set the IPO price within a SEBI-regulated band, where the cap is between 105% and 120% of the floor.
- The band is announced at least two working days before opening, and bidding runs for at least three working days.
- Anchors bid a day early. Since late 2025, 40% of the anchor book is reserved for mutual funds, insurers and pension funds.
- The retail quota remains 35% under Regulation 6(1); the proposal to cut it was withdrawn.
- Oversubscribed issues are almost always priced at the cap, and bids below the final price are rejected.
- Read category-wise demand, not just the headline subscription figure, before treating a strong book as a listing signal.