Rays of Belief Limited — IPO Business Report
Healthcare Services — Neurodevelopmental Disorder (NDD) Intervention (For-Profit Social Enterprise).
1. Overview
Rays of Belief Limited, operating under the consumer brand "Mom's Belief", is a For-Profit Social Enterprise that provides personalised intervention plans for children with Neurodevelopmental Disorders (NDDs) — including Autism Spectrum Disorder (ASD), ADHD, Down Syndrome, Cerebral Palsy, Intellectual Disability, Learning Disabilities and Global Developmental Delays. The Company was founded to address four structural barriers around NDD care in India — lack of awareness, limited access, inadequate quality of care and affordability — with an intervention model designed to enable parents and families to act as co-therapists in a child's developmental journey.
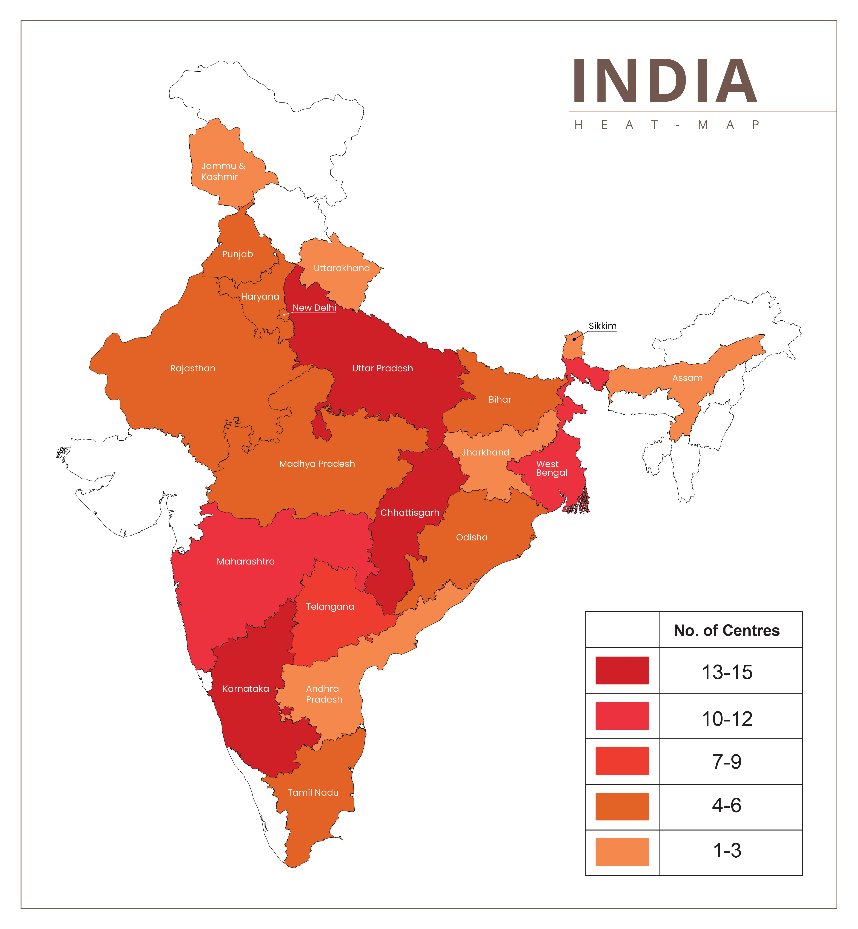
Incorporated in 2017 and having opened its first centre in Gurgaon in 2018, the Company has scaled from 71 centres in Fiscal 2023 to 136 centres as of March 31, 2026 (excluding three recently acquired overseas centres). Based on number of centres, it ranks 1st in India and 7th globally among players in the behavioural-health domain (Source: CARE Report). Its network spans 57 cities across 20 states and union territories, with a deliberately decentralised footprint of 42 Tier-1, 77 Tier-2 and 17 Tier-3 centres — a positioning aimed at underserved semi-urban geographies where developmental care has historically been scarce. The Company has served upwards of 58,000 children since 2018, including 9,205 children in Fiscal 2026.
Financially, the Company has scaled rapidly and turned profitable. Revenue from Operations grew from ₹30.61 Crore (FY24) to ₹81.66 Crore (FY26), while Profit After Tax stood at ₹4.96 Crore in FY26.
2. Business Model and Revenue Streams
The Company runs an asset-light, lease-based centre model. All centres operate on leasehold premises with tenures of 11 months to 3 years, allowing new-centre rollout with limited upfront capital expenditure and high scalability. This structure is central to the equity story but is also the Company's single largest disclosed risk, since immovable fit-out capex (~30–37% of centre capex) is non-transferable if a lease is not renewed.
Revenue Composition (FY26 vs FY24)(₹ Cr)
| Revenue Stream | FY26 (Consolidated) | FY25 (Standalone) | FY24 (Standalone) |
|---|---|---|---|
| Revenue from centre operations | 26.17 | 21.31 | 19.33 |
| Revenue from online services | 0.39 | 0.46 | 0.70 |
| Export of services | 20.87 | 14.44 | 10.44 |
| Overseas centre revenue | 34.09 | Nil | Nil |
| Total Revenue from Operations | 81.66 | 36.42 | 30.61 |
Note: FY26 revenue mix is materially reshaped by the US acquisition — Overseas centre revenue of ₹34.09 Cr and export services of ₹20.87 Cr together account for the majority of the FY26 step-up.
Pricing, Contracts and Concentration
- Pricing model: Fee-based personalised intervention plans delivered through centres, schools, online therapy and home-based kits; services primarily cater to children aged 18 months to 12 years, with specialised programs up to age 15.
- Partnership dependency: In FY26, 73.79% of revenue came from centre operations, of which 26.52% flowed through "Company Learning Centres in partnership with Licensed Professionals" — arrangements that are terminable at will by either party, creating a structural revenue-continuity risk.
- Related-party concentration: 25.56% of FY26 Revenue from Operations was derived from export of support services to Promoter-Group entities (Carving Futures Pte. Ltd. and Carving Futures Inc.), a significant conflict-of-interest and concentration exposure.
- Geographic concentration: 15.36% of FY26 revenue came from centres in Uttar Pradesh and Karnataka.
3. Products and Service Portfolio
The Company operates five centre models in India plus its newly added overseas practice. As of March 31, 2026:
| Centre Model | No. of Centres |
|---|---|
| Company Learning Centres in Partnership with Licensed Professionals | 104 |
| Company Learning Centres | 19 |
| School Collaboration Centres | 11 |
| Centre of Excellence and Research (COER) | 1 |
| Upskilling Academy | 1 |
| Total (India) | 136 |
| Overseas centres (USA — Virginia) | 3 |
Service Suite
A comprehensive, multidisciplinary suite spanning early intervention, parental guidance, occupational therapy, language/speech therapy and family-support programs.
Centres are equipped with 150+ teaching tools (sensory equipment, puzzles, worksheets); home-based learning kits carry 2,000+ teaching tools with structured follow-ups and progress monitoring.
Digital delivery via teletherapy and online programs, extending reach beyond the physical centre network.
Operating Metrics (capacity / productivity proxy)
| Metric | FY26 | FY25 | FY24 |
|---|---|---|---|
| Total children served during the Fiscal | 9,205 | 8,585 | 9,344 |
| Fresh enrolments during the Fiscal | 6,903 | 6,512 | 7,307 |
| Total centres | 139 | 111 | 71 |
| Avg. revenue per centre per month (₹ Cr) | 0.23 | 0.21 | 0.18 |
| Avg. monthly attrition — clinical professionals | 4.41% | 3.33% | 4.49% |
| Avg. monthly attrition — all employees | 3.67% | 2.89% | 3.94% |
The primary revenue driver is the partnership-based Company Learning Centre model (104 of 136 centres). The emerging segments are the overseas (US) practice, School Collaboration Centres and the R&D/upskilling infrastructure funded by the IPO.
4. Key Business Strengths
- Market Leadership: India's largest For-Profit Social Enterprise for NDD intervention by number of centres — 1st in India, 7th globally.
- Pan-India Penetration: Deliberate presence across Tier-1, Tier-2 and Tier-3 cities (57 cities, 20 states/UTs), reaching underserved geographies competitors overlook.
- Asset-Light Scalability: Lease-based, low-capex centre model enabling rapid, capital-efficient rollout and high scalability.
- Accessibility Focus: Multi-channel delivery — physical centres, schools, online therapy and home kits — plus insurance for enrolled children and frontline-worker (ASHA/ANM) training programs.
- Comprehensive, Client-Focused Care: In-house clinical team delivering development-focused, personalised intervention plans grounded in established clinical methodologies.
- R&D and Digital Adaptability: Evidence-based programs supported by a dedicated R&D team; leveraging teletherapy and data/AI to improve intervention efficacy.
- Experienced Management: Led by founder Nitin Bindlish alongside 340+ full-time clinical professionals with deep sector expertise.
- Demonstrated Turnaround: Scaled revenue while turning profitable, evidencing a sustainable, repeatable execution model.
5. Future Growth Strategy
- Network Expansion with Cost Efficiency: Deploy ₹41.36 Crore of IPO proceeds to set up 319 new centres between Fiscal 2027–2029, deepening penetration in Tier-2 and Tier-3 cities through the low-capex organic rollout model.
- Inorganic and International Growth: Expand via acquisitions and strategic alliances; build out the acquired US (Virginia) practice and enter the UAE and UK through incorporated group entities (Carving Futures SPV Limited and Carving Futures UK Private Limited).
- Clinical Talent Development: Establish seven new "Upskilling Academies" to recruit, train, upskill and retain clinical professionals — directly addressing the elevated clinical attrition risk.
- R&D and Technology Integration: Set up six "Centres of Excellence and Research" (COER) and integrate AI/ML and predictive modelling into therapy delivery to improve outcomes and standardise best practices.
- Service Portfolio Deepening: Introduce new offerings and improve intervention plans to drive enrolments, cross-sell and value leadership at affordable price points.
- Brand Building: Grow "Mom's Belief" brand awareness and loyalty through ATL/BTL marketing, digital channels and the Licensed-Professional network to capture the growing NDD-affected population in India.

Delete Comment?
Are you sure you want to delete this comment? This action cannot be undone.
Discussion
Join the discussion!
Log In to CommentNo comments yet. Be the first to share your thoughts!