ABH Healthcare Limited
Sector: Healthcare Services — Multi-Specialty Hospitals
1. Overview
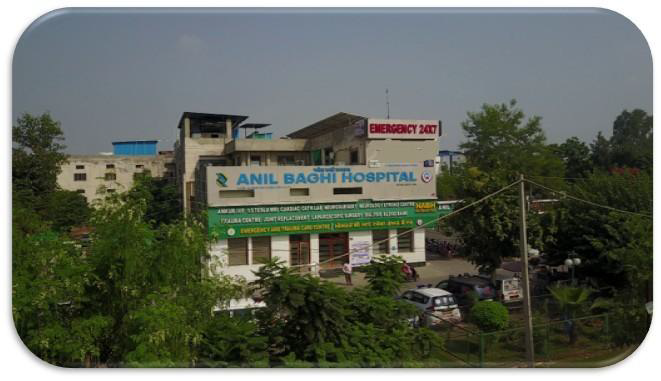
ABH Healthcare Limited ("ABH" or the "Company") owns and operates a single 150-bed multi-specialty tertiary care hospital in Ferozepur, Punjab, run under the flagship "Anil Baghi Hospital" brand. The hospital was established in 1985 with just 30 beds and was acquired by the Company in 2022; the Company itself was originally incorporated on March 2, 2021. Since acquisition, management has consistently reinvested — expanding bed capacity, widening the clinical workforce and adding specialties — taking the facility from 75 beds (FY2022) to 100 beds (FY2024) and 150 beds (FY2026).
The Company's positioning is deliberately regional and value-focused: delivering specialised tertiary care in Tier-3 Punjab while balancing clinical quality with affordability. As of the RHP, the hospital offers 25 medical specialties spanning cardiac sciences, neurology, minimally invasive spine & brain surgery, gastroenterology, laparoscopic & bariatric surgery, urology, nephrology, orthopedics & joint replacement, and adult & neonatal critical care. Clinical depth is anchored by its U.S.-trained promoter-doctors — Dr. Saurabh Baghi (Managing Director; MD Internal Medicine, Brooklyn Hospital Center; cardiology fellowship, Mount Sinai) and Dr. Vaishali Saini (ABPN-certified Neurologist, New York Presbyterian–Cornell) — alongside founder Dr. Kamal Baghi.
On scale, ABH reported consolidated revenue from operations of ₹52.51 crore and PAT of ₹5.64 crore in FY2026, up from ₹41.38 crore and ₹1.66 crore respectively in FY2024. As of June 30, 2026, the hospital was staffed by 37 doctors and 101 nurses. The facility is NABH-accredited (2021), was awarded NABH Digital Standards in FY2025, and reports a ~97% success rate while treating 5,000+ patients annually since 2023.
Competitively, ABH is a dominant regional super-specialty provider in a Tier-3 catchment with limited organised competition, differentiated by its brand legacy (35+ years), doctor-led leadership and deep empanelment with government and insurance payors.
2. Business Model and Revenue Streams
ABH operates an owned-and-operated single-hospital model, supplemented by an emerging asset-light expansion strategy through LLPs and affiliations. Revenue is derived predominantly from in-patient (IPD) care, with a growing out-patient (OPD) funnel and ancillary pharmacy and laboratory income.
Revenue by Care Setting (Standalone)
| Metric | FY2026 | FY2025 | FY2024 |
|---|---|---|---|
| In-patient (IPD) revenue (₹ cr) | 42.91 | 40.90 | 34.76 |
| Out-patient (OPD) revenue (₹ cr) | 4.97 | 5.45 | 4.62 |
| IPD discharged patients (count) | 6,387 | 6,339 | 5,723 |
| OPD consultations (count) | 53,212 | 53,556 | 43,415 |
| Number of surgeries (count) | 1,927 | 2,211 | 2,137 |
| Revenue from operations (₹ cr) | 51.04 | 48.92 | 41.38 |
Payor Mix — A Government-Anchored, Diversified Book
ABH earns from a diversified payor mix, with a rising skew toward government schemes and PSUs, reflecting deep empanelment across ECHS, Railways, FCI, BSNL and Ayushman Bharat (Sarbat Sehat Bima Yojana), plus 30+ private insurers and TPAs.
| Payor Category (in-patient, ₹ in Cr) | FY2026 | % | FY2025 | % | FY2024 | % |
|---|---|---|---|---|---|---|
| Govt. Schemes & PSUs | 26.75 | 52.4% | 22.98 | 47.0% | 17.97 | 43.4% |
| Insurance & TPAs | 4.87 | 9.5% | 3.66 | 7.5% | 3.79 | 9.2% |
| Self-Pay | 16.26 | 31.9% | 19.72 | 40.3% | 17.62 | 42.6% |
Client / payor concentration risk: the growing dependence on government schemes (52.4% of in-patient revenue in FY2026, up from 43.4% in FY2024) improves volume visibility but introduces reimbursement-rate and receivables risk — consistent with the high trade receivables on the balance sheet. Self-pay share has declined, modestly compressing pricing flexibility.
3. Products and Service Portfolio
ABH functions as a one-stop tertiary facility across 25 specialties. Beyond core clinical care, the Company runs ancillary revenue lines and is building a distributed care network.
Bed Configuration (FY2026) — Capacity & Case-Mix
| Unit | Beds | Unit | Beds |
|---|---|---|---|
| ICU | 70 | Private Rooms (Super Deluxe) | 15 |
| Pediatric Unit | 9 | Private Rooms | 6 |
| Emergency | 7 | Female / Male Ward | 3 / 5 |
| Dialysis* | 10 | Semi Ward (Twin Share) | 4 |
| Labour & Delivery / Antenatal | 2 / 3 | Isolation | 1 |
| Total operative beds | 135 | Total bed capacity | 150 |
*Includes dialysis beds under the Five Creeks Healthcare LLP arrangement. The high ICU-to-total ratio (70 of 150 beds) underscores the tertiary/critical-care orientation.
Ancillary Services
- Pharmacy ("Anil Baghi Pharmacy"): round-the-clock, outsourced; Company's share of income ₹2.76 cr (FY2026) vs ₹1.74 cr (FY2024).
- Pathology laboratory: outsourced, EHR-integrated with dry-chemistry and automated culture systems; billing share ₹3.50 cr (FY2026).
Distributed / Asset-Light Vehicles
- Five Creeks Healthcare LLP (90% interest) — a Punjab State Health Agency-recognised dialysis treatment centre.
- ABH Clinics LLP (90% interest) — the Company's first off-campus outpatient clinic.
Key Hospital Operating Metrics
| KPI | FY2026 | FY2025 | FY2024 |
|---|---|---|---|
| Total bed capacity (count) | 150 | 150 | 100 |
| Operational beds (count) | 125 | 125 | 85 |
| Bed Occupancy Rate (%) | 47% | 49% | 63% |
| Average Revenue per Occupied Bed (ARPOB, ₹) | 19,992 | 18,245 | 17,808 |
| Average Length of Stay (ALOS, days) | 3.36 | 3.54 | 3.41 |
Analyst note: the occupancy rate has fallen from 63% (FY2024) to 47% (FY2026) even as bed capacity was expanded from 100 to 150 — a classic capacity-addition dilution. However, ARPOB rose to ₹19,992 and EBITDA margin nearly doubled to 28.3%, indicating a richer case-mix and operating leverage offsetting lower utilisation. Filling the expanded (and board-approved additional 30) beds is the key throughput lever for future earnings.
4. Key Business Strengths
- Doctor-led professional management — U.S.-trained promoter-clinicians with proven execution across four decades of hospital operations.
- Quality clinical talent moat — ability to attract and retain renowned specialists via advanced infrastructure, 24×7 super-specialist availability and competitive packages.
- Diversified specialties and payor mix — 25 specialties and a broad government-plus-insurance-plus-self-pay revenue base reducing single-stream dependence.
- Regional brand legacy — the 35+ year "Anil Baghi Hospital" name commands strong recall and referral flow in its Ferozepur catchment.
- Robust IT and modern equipment — CPOE + EHR platform, in-house server infrastructure and NABH Digital Standards accreditation.
5. Future Growth Strategy
- Fill and expand bed capacity — utilise the enlarged 150-bed base and board-approved additional 30 beds within existing premises to lift occupancy and throughput.
- Attract and retain clinicians — structured training, DNB programmes and global-standard mentoring to deepen the specialist bench.
- Digital-first operations — video consultations, paperless documentation, e-ICU and revenue-cycle-management systems to improve efficiency and patient reach.
- Hub-and-spoke reach — establish urgent care centres and off-campus OPD clinics to funnel referrals into the flagship hospital.
- Asset-light inorganic growth — expand via revenue-sharing, management-fee models and selective acquisitions (funded partly by IPO proceeds earmarked for unidentified acquisitions), preserving a lean capital base.
- Payor and empanelment expansion — broaden government-scheme and insurance tie-ups to sustain volume-led growth.



Delete Comment?
Are you sure you want to delete this comment? This action cannot be undone.
Discussion
Join the discussion!
Log In to CommentNo comments yet. Be the first to share your thoughts!