A-One Steels India Limited
Sector: Integrated Steel Manufacturing (Secondary Steel – Long & Flat Products)
1. Overview
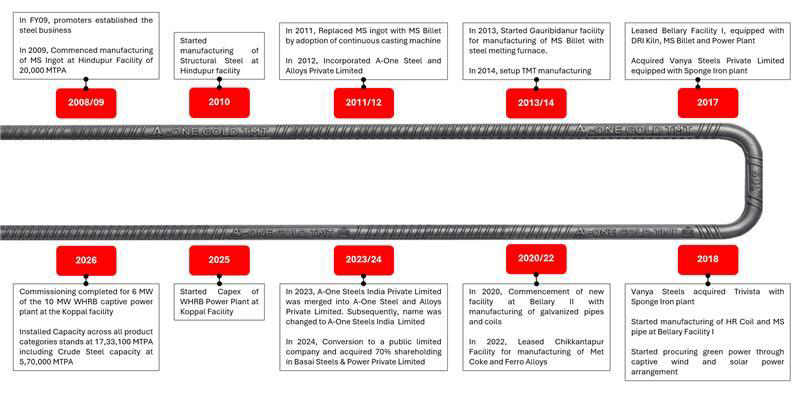
A-One Steels India Limited is a backward/vertically integrated steel manufacturer based in southern India, producing long and flat steel products alongside industrial inputs used in steelmaking. The company was incorporated in April 2012 in Bangalore as A-One Steel and Alloys Private Limited and commenced operations in 2013 with a single product — MS billets — at its Gauribidanur Facility with an installed capacity of roughly 20,000 MTPA. Its manufactured portfolio now spans 10 steel and industrial products.
The integrated value chain runs from sponge iron (DRI) to MS billets, which are converted into finished products including TMT bars, HR coils, CR coils, HR (MS) pipes, CR pipes and galvanised (GP) pipes and tubes. The company also manufactures met coke and ferro alloys (silicon manganese, ferro silicon) for open-market sale. Intermediate products are predominantly consumed captively (98.89% of MS billets and 88.81% of HR & CR coils in Fiscal 2026), with surplus sold externally.
Operations are conducted through six manufacturing units across Karnataka and Andhra Pradesh. Aggregate installed capacity stood at 17,33,100 MTPA as of March 31, 2026, with crude steel capacity of 5,70,000 MTPA operating at 89.14% utilisation. Facilities lie within approximately 450 km of major ports (Krishnapatnam, Ennore, New Mangalore, Goa-Mormugao) and the Bellary/Koppal units sit within 100 km of the Bellary–Koppal iron ore belt.
In Fiscal 2026, the company reported Revenue from Operations of ₹4,148.57 Cr, EBITDA of ₹303.64 Cr (7.29% margin) and PAT of ₹127.41 Cr (3.06% margin), a sharp recovery from PAT of ₹7.71 Cr in Fiscal 2025. Competitive differentiation rests on backward integration, raw-material proximity and a high share of renewable power (83.20% of electricity consumption)). Balance-sheet leverage remains elevated, with Net Debt of ₹985.37 Cr and Debt/Equity of 1.17x.
2. Business Model and Revenue Streams
Core Model
Integrated manufacturer + trader: Revenue combines manufactured products (long steel, flat steel, industrial products), traded raw materials and intermediates (coal, iron ore, scrap, MS billets, sponge iron) and by-product sales (dust, fly ash, charcoal, mill scale).
Trading exposure is material: "Other trading sales" contributed 18.22% of revenue in Fiscal 2026 (₹755.94 Cr); coal (10.45%) and iron ore (7.45%) are sizeable line items in the product mix.
Raw material intensity: Cost of raw materials consumed was 84.05% of Revenue from Operations in Fiscal 2026 (86.22% in FY25; 88.53% in FY24) — margins are highly sensitive to iron ore, coal and scrap price movements.
Revenue by Sales Channel (₹ Crore)
| Channel | FY26 Count | FY26 Revenue | FY26 % | FY25 Revenue | FY25 % | FY24 Revenue | FY24 % |
|---|---|---|---|---|---|---|---|
| Direct sale channels | 1,246 | 1,235.02 | 29.77% | 1,025.87 | 28.97% | 809.16 | 21.10% |
| Distributors | 32 | 607.42 | 14.64% | 664.89 | 18.78% | 790.23 | 20.61% |
| Institutional customers | 57 | 232.33 | 5.60% | 294.72 | 8.32% | 245.32 | 6.40% |
| Other intermediary sales* | 380 | 1,317.86 | 31.77% | 1,008.13 | 28.47% | 904.17 | 23.58% |
| Other trading sales# | – | 755.94 | 18.22% | 547.74 | 15.47% | 1,085.33 | 28.31% |
| Total | 1,715 | 4,148.57 | 100% | 3,541.35 | 100% | 3,834.21 | 100% |
*Sale of semi-finished/intermediate products (MS billets, HR/CR coil, sponge iron) to customers outside the direct, distributor and institutional channels.
#Sale of procured raw materials/intermediates (scrap, iron ore, MS billets, coal).
Shift toward direct retail: Direct sale channels rose from 21.10% (FY24) to 29.77% (FY26) of revenue; channel count grew from 1,041 to 1,246.
Distributor base shrinking: Authorised distributors fell from 50 (FY25) to 32 (FY26); only four had long-term arrangements as of March 31, 2026.
Institutional clients include Sobha Limited, NCC Limited, Zetwerk Manufacturing Businesses, Amara Raja Infra, Casa Grande Garden City Builders, among others, serviced by a 63-member sales and marketing team.
Pricing and Contract Structure
| Parameter | Authorised Distributors | Direct Retail Sales |
|---|---|---|
| Agreement validity | 5 years with mutual renewal | Rolling purchase-order based |
| Pricing model | Ex-plant / landed rate with volume incentives | Fixed margin / dynamic pricing |
| Territory rights | Exclusive / non-exclusive by product & region | No exclusivity |
| Credit terms | 21–60 days (+15 days interest-free extension) | 21–60 days / advance / delivery against payment |
| Sales targets | Quarterly / annual slabs | Not mandated |
Geographic Concentration (₹ Crore)
| State | FY26 Revenue | FY26 % | FY25 Revenue | FY25 % | FY24 Revenue | FY24 % |
|---|---|---|---|---|---|---|
| Karnataka | 2,276.09 | 54.86% | 2,025.78 | 57.20% | 1,929.11 | 50.31% |
| Andhra Pradesh | 470.90 | 11.35% | 343.80 | 9.71% | 491.22 | 12.81% |
| Tamil Nadu | 298.97 | 7.21% | 234.58 | 6.62% | 277.63 | 7.24% |
| Maharashtra | 249.13 | 6.01% | 254.81 | 7.19% | 249.27 | 6.50% |
| Telangana | 182.13 | 4.39% | 203.70 | 5.75% | 234.87 | 6.13% |
| Others | 671.35 | 16.18% | 479.11 | 13.53% | 652.11 | 17.01% |
| Total | 4,148.57 | 100% | 3,541.78 | 100% | 3,834.21 | 100% |
Home-state dependence: Karnataka alone contributes over 50% of revenue in each of the last three fiscals; the five southern/western core states account for ~84%.
Customer Concentration
- Top 10 customers: ₹1,157.45 Cr (27.90%) in FY26; 25.48% in FY25; 26.66% in FY24.
- Largest customer (Shri Tirupati Steels): ₹221.21 Cr (5.33%); no single customer exceeded 7.00% in the last three fiscals.
- Related-party linkage: Bellary Tubes Corporation (4.73% of FY26 revenue) was a related party until June 12, 2024.
- Base of 1,715 customers in FY26 (1,618 in FY25; 1,578 in FY24).
3. Products and Service Portfolio
Product-wise Revenue (₹ Crore)
| Product | FY26 Revenue | FY26 % | FY25 Revenue | FY25 % | FY24 Revenue | FY24 % |
|---|---|---|---|---|---|---|
| TMT Bars | 1,203.26 | 29.00% | 1,181.83 | 33.37% | 1,118.65 | 29.18% |
| Pipes & Tubes (HR/MS, GP, CR) | 900.29 | 21.70% | 805.32 | 22.74% | 725.46 | 18.92% |
| Sponge Iron | 452.58 | 10.91% | 411.86 | 11.63% | 488.39 | 12.74% |
| Coal | 433.48 | 10.45% | 256.02 | 7.23% | 387.04 | 10.09% |
| Iron Ore | 309.11 | 7.45% | 111.85 | 3.16% | 262.60 | 6.85% |
| Met Coke | 276.62 | 6.67% | 173.15 | 4.89% | 158.54 | 4.13% |
| MS Billets | 238.09 | 5.74% | 234.43 | 6.62% | 257.80 | 6.72% |
| Coil (GP, CR, HR) | 188.19 | 4.54% | 219.02 | 6.18% | 75.77 | 1.98% |
| Ferro Alloys (SiMn, FeSi) | 67.11 | 1.62% | 60.92 | 1.72% | 69.86 | 1.82% |
| Scrap | 63.92 | 1.54% | 72.70 | 2.05% | 282.79 | 7.38% |
| Others (by-products) | 15.91 | 0.38% | 14.25 | 0.40% | 7.30 | 0.19% |
| Total | 4,148.57 | 100% | 3,541.35 | 100% | 3,834.21 | 100% |
Primary Revenue Drivers vs Emerging Segments
- Core franchise: TMT bars, pipes & tubes and sponge iron together contributed 61.61% of FY26 revenue (₹2,556.13 Cr).
- Branded retail: TMT bars and steel pipes are marketed under the "A-One Gold" brand; TMT bars use German Thermex Technology and comply with IS:1786.
- Scaling segments: Met coke revenue rose 74.5% from FY24 to FY26 (₹158.54 Cr → ₹276.62 Cr) on capacity additions at Chikkantapur; pipes & tubes grew 24.1% over the same period.
- Green products: TMT bars (Fe 550D CRS, Fe 500D CRS, Fe 550 CRS) from Gauribidanur and Hindupur, and HR coil / HR (MS) pipes from Bellary I, hold CII GreenPro Ecolabel certification. A Green Steel Certificate (August 27, 2026) rates FY26 TMT output of 1,80,351 tonnes at 5 stars with emission intensity of 0.67 tCO2e/tfs.
Facility-wise Installed Capacity and Utilisation (Fiscal 2026)
| Facility | Product | Installed Capacity (MTPA) | Production (MT) | Utilisation |
|---|---|---|---|---|
| Bellary Facility I (leased) | MS Billet | 2,50,000 | 1,98,858 | 79.54% |
| Sponge Iron | 1,00,000 | 98,265 | 98.27% | |
| HR (MS) Pipe | 1,60,000 | 1,32,507 | 82.82% | |
| HR Coil | 2,00,000 | 1,70,384 | 85.19% | |
| Power Plant | 20 MW | 5.85 MW | 29.31% | |
| Gauribidanur (owned) | MS Billet | 2,00,000 | 1,99,759 | 99.88% |
| TMT Bar | 2,16,000 | 1,80,877 | 83.74% | |
| Chikkantapur (leased) | Met Coke | 96,000 | 90,776 | 94.56% |
| Ferro Alloys | 37,100 | 23,719 | 63.93% | |
| Power Plant | 12 MW | 7.20 MW | 60.00% | |
| Hindupur (owned) | MS Billet | 1,20,000 | 94,228 | 78.52% |
| TMT Bar | 1,20,000 | 72,466 | 60.39% | |
| Bellary Facility II (owned) | GP Pipe | 84,000 | 56,282 | 67.00% |
| Koppal – Vanya Steels (owned) | Sponge Iron | 1,50,000 | 1,54,421 | 102.95% |
| Power Plant (WHRB) | 6 MW | 1.08 MW | 18.00% |
Crude Steel Capacity Trend
| Particulars | FY26 | FY25 | FY24 |
|---|---|---|---|
| Installed capacity (MTPA) | 5,70,000 | 5,70,000 | 4,55,000 |
| Actual production (MT) | 5,08,088 | 4,53,488 | 3,95,890 |
| Utilisation | 89.14% | 79.56% | 87.01% |
4. Key Business Strengths
- Backward integration: Presence from sponge iron to finished TMT bars, coils and pipes, with 98.89% captive consumption of MS billets reducing third-party input dependence.
- Diversified product mix: 10 manufactured products; the largest category (TMT bars) is 29.00% of revenue.
- Raw-material proximity: Bellary and Koppal units within 100 km of the iron ore belt; all facilities within ~450 km of four major ports.
- Multi-channel distribution: 1,246 direct retail channels, 32 distributors and 57 institutional customers, with no customer above 7% of revenue.
- High entry barriers: Established capacity, regulatory approvals and access to cost-efficient inputs in a capital-intensive industry.
- Brand presence: "A-One Gold" brand for TMT bars and pipes, supported by celebrity endorsement and multi-channel marketing across southern India.
- Green energy leadership: 83.20% renewable share in electricity consumption and CII GreenPro-certified TMT bars, HR coils and pipes.
- Experienced promoters: Founders with 18+ years each in the steel industry, backed by a professional management team.
5. Future Growth Strategy
- Portfolio and pan-India expansion: Add product specifications for automotive, infrastructure, engineering and consumer sectors, and extend reach beyond the five core states via new distributors and tenders.
- Koppal capacity build-out: Commission a 6,00,000 MTPA iron ore beneficiation plant (50% in FY27, 50% in FY28) and complete the 10 MW WHRB power plant (6 MW operational; balance by Q2 FY27).
- Logistics cost reduction: Commission a railway siding over 23.08 acres at Koppal by June 2027; inward freight was 5.43% of raw material cost in FY26.
- Deeper backward integration: Evaluate a pelletisation plant, an alloy billet plant and a crash barrier plant on 98.61 acres of vacant land at Koppal.
- Customer and wallet-share growth: Expand the customer base and increase business share among existing customers, including repeat buyers of TMT bars and pipes.
- Inorganic growth: Pursue strategic acquisitions and leases of existing manufacturing assets, as done at Bellary I and Chikkantapur.
- Deleveraging: Deploy ₹250.00 Cr of Fresh Issue proceeds to prepay borrowings, targeting lower interest costs and improved debt-equity.
- Brand building: Continue investment in "A-One Gold" through digital, outdoor, print and endorsement-led campaigns.
Disclaimer: This report is based solely on disclosures in the Red Herring Prospectus and is intended for informational purposes only. It does not constitute investment advice.


Delete Comment?
Are you sure you want to delete this comment? This action cannot be undone.
Discussion
Join the discussion!
Log In to CommentNo comments yet. Be the first to share your thoughts!