Moneyview Limited
1. Overview
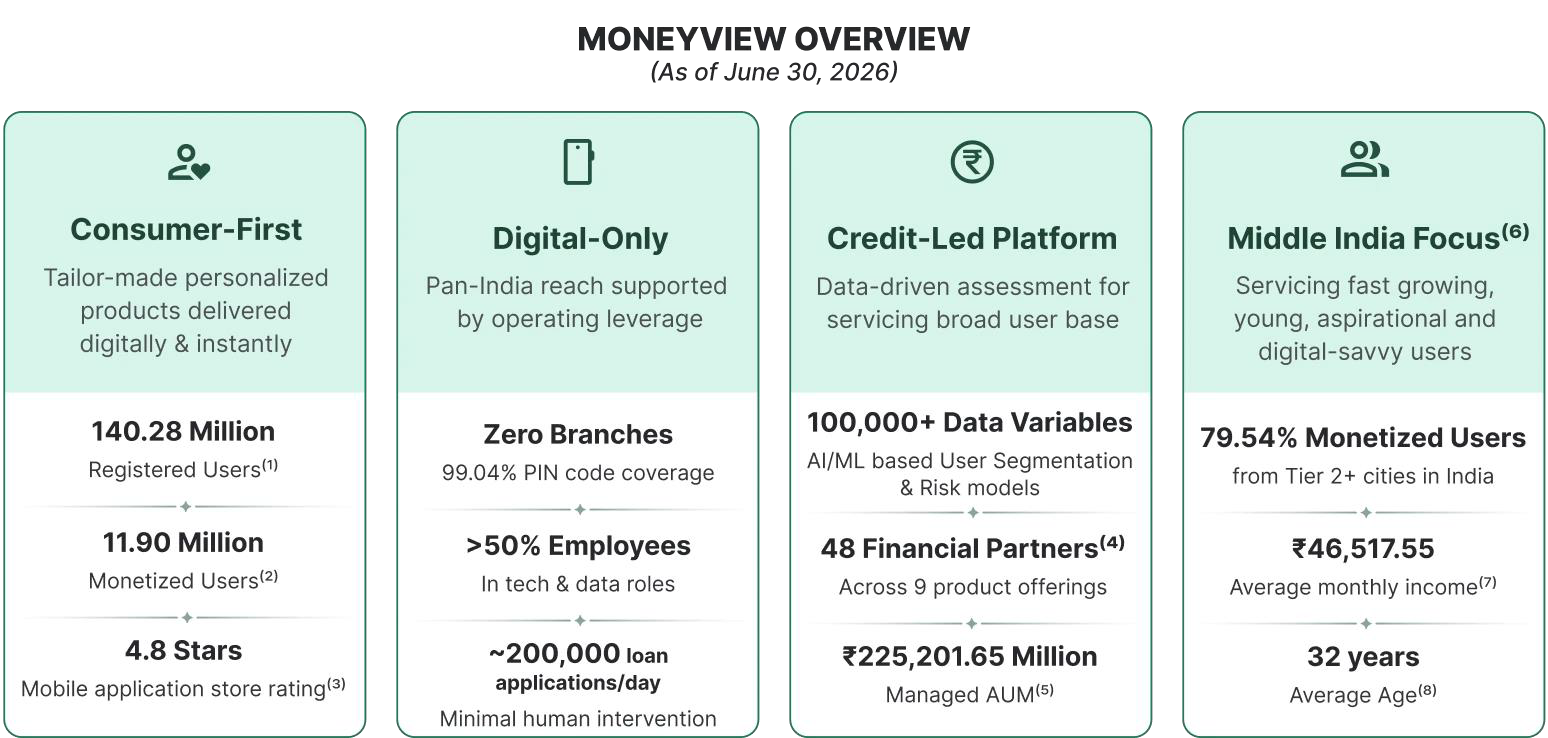
Moneyview Limited (originally incorporated as Whizdm Innovations Private Limited in 2014) is a consumer-focused, digital-only, credit-led financial services platform built for "Middle India" — households with annual income of ₹3,00,000–₹11,00,000. The Company was founded by Puneet Agarwal and Sanjay Aggarwal, who remain its Promoters and Executive Directors, and operates entirely through its Moneyview mobile application, which carries a 4.8-star rating as of June 30, 2026.
The Company's core operating model is that of a two-sided digital network: it connects users seeking credit and other financial products with a panel of 48 Financial Partners (banks, NBFCs, insurers and other institutions) as of June 30, 2026, including its own material NBFC subsidiary, Whizdm Finance Private Limited ("WFPL"). Moneyview does not operate physical branches — as of June 30, 2026 it served 99.04% of India's pin codes digitally, processing close to 2,00,000 loan applications per day.
Scale has grown rapidly: Registered Users rose from 83.27 million (March 2024) to 134.14 million (March 2026) — a 26.92% CAGR — and further to 140.28 million by June 30, 2026. Of these, 11.90 million were "Monetized Users" (users who have availed at least one revenue-generating product), up from 4.62 million in Fiscal 2024. Managed AUM under the flagship personal-loan program stood at ₹22,520.17 Cr as of June 30, 2026, against which the Company posted Fiscal 2026 total revenue from operations of ₹3,351.16 Cr and restated PAT of ₹242.71 Cr.
Competitively, Moneyview operates in a space with no direct listed comparable in India; the RHP benchmarks it against a mixed peer set of digital-platform players (PB Fintech/Policybazaar, One97 Communications/Paytm, OnEMI Technology Solutions) and listed consumer-credit NBFCs (Bajaj Finance, SBI Cards) — reflecting Moneyview's positioning at the intersection of a technology platform and a credit business.
2. Business Model and Revenue Streams
How the platform earns money
Moneyview's personal loans — its flagship and largest product — are disbursed through two distinct channels, each with a different revenue and risk profile:
- Platform Partners (banks and NBFCs integrated onto the platform): Moneyview acts as a Lending Service Provider (LSP), earning origination fees for user acquisition/onboarding and servicing fees for managing the loan lifecycle (collections, customer support). The Company also shares a portion of credit losses through Default Loss Guarantee (DLG) arrangements, capped contractually at a maximum of 5% of the disbursed loan portfolio.
- WFPL (own NBFC subsidiary): On-balance-sheet lending, where Moneyview earns interest income and bears the net interest margin (spread between interest income and cost of borrowed funds), along with the entire credit risk on these loans.
This structure maps directly onto the P&L: Fees and commission income (LSP fees), Interest income (WFPL on-book loans), Finance costs (cost of borrowings funding WFPL's book), and Impairment of financial instruments (DLG share of losses + WFPL's own credit losses).
Revenue and profitability trend (Fiscal, ₹ Crore unless stated)
| Metric | FY2024 | FY2025 | FY2026 | FY26 vs FY25 |
|---|---|---|---|---|
| Total revenue from operations | 1,342.37 | 2,339.15 | 3,351.16 | +43.3% |
| Total income | 1,389.24 | 2,378.53 | 3,404.27 | +43.1% |
| Net Loan Revenue | 1,086.47 | 1,447.31 | 1,976.06 | +36.5% |
| Loan Margin (%) | 7.48% | 8.21% | 8.55% | +34 bps |
| Operating Expenses / Total Income | 56.42% | 41.43% | 34.84% | −657 bps |
| Operating Profit | 302.63 | 461.96 | 790.02 | +71.0% |
| Restated PAT | 171.15 | 240.28 | 242.71 | +1.0% |
| Loan Disbursals | 14,527.16 | 17,621.12 | 23,098.52 | +31.1% |
| Managed AUM (year-end) | 12,884.83 | 16,715.14 | 21,380.14 | +27.9% |
Note: FY2026 PAT growth is muted relative to Operating Profit growth because of a ₹206.65 Cr exceptional item (net loss) recorded in Fiscal 2026; profit before exceptional items grew 65.4% year-on-year to ₹397.34 Cr.
Concentration and dependency
Moneyview's dependence on its lending-partner network is a structurally important feature of the model: its top ten Financial Partners contributed 39.02% (Q1 FY27), 37.36% (FY26), 46.82% (FY25) and 56.78% (FY24) of revenue from operations, respectively — a dependency that is declining as the Company diversifies its partner base, but remains material. Marketing and direct-sourcing cost efficiency has also improved, falling from ₹424.28 Cr (2.92% of Loan Disbursals) in FY2024 to ₹439.11 Cr (1.90% of Loan Disbursals) in FY2026.
3. Products and Service Portfolio
Product architecture
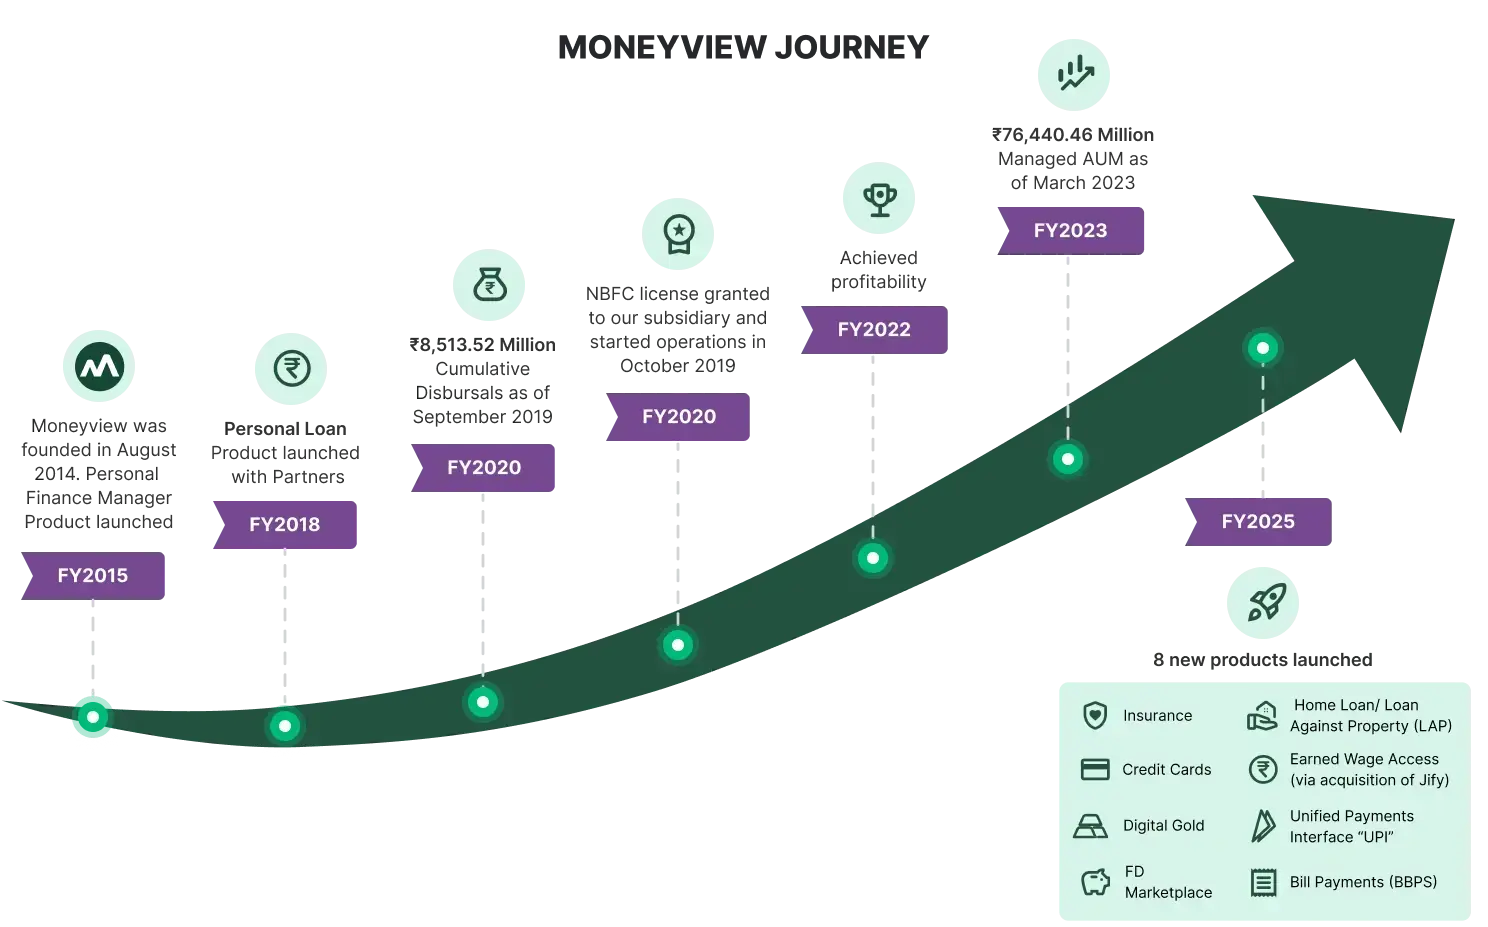
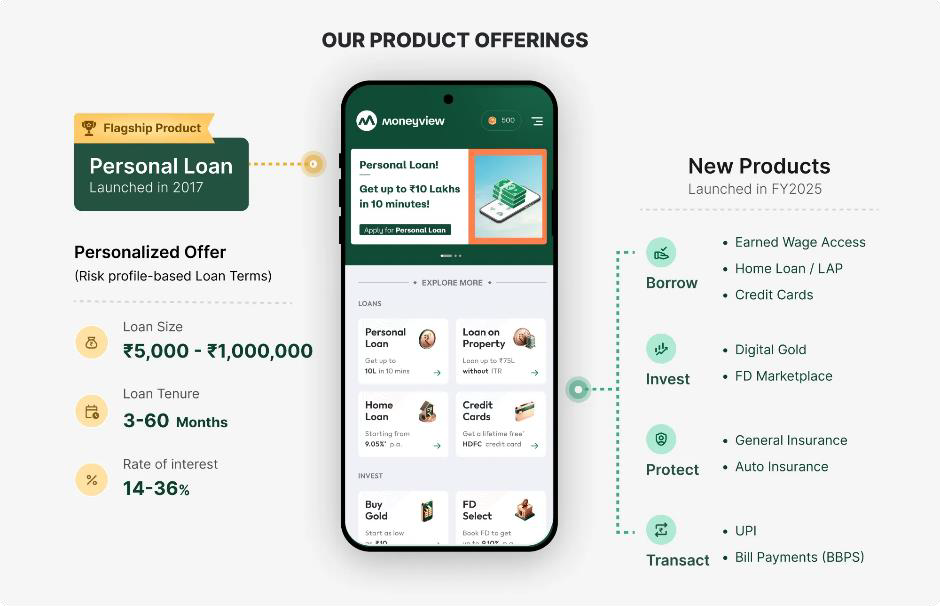
The platform is organized around four categories — Borrow, Transact, Invest and Protect — but personal loans remain the flagship and dominant revenue driver. Since August 2024, the Company has layered on credit cards, earned wage access, home loans, loans against property, insurance, digital gold, UPI transactions and bill payments, all delivered through the same app-based, paperless journey. Depth of detail on the newer (non-lending) categories was not disclosed within the RHP pages reviewed for this report.
Personal Loans — flagship product detail
Instant, fully digital loans of up to ₹10 lakh, with repayment tenures of up to 60 months
Underwritten via in-house AI/ML segmentation and risk models using both traditional and alternative data
22 regulated lending entities (REs) partnered as of June 30, 2026 (including WFPL)
6.61 million users were being serviced with outstanding loans as of June 30, 2026
AUM composition — On-book vs Off-book (₹ Crore)
| Metric | FY2024 | FY2025 | FY2026 | Q1 FY27 (Jun 2026) |
|---|---|---|---|---|
| Managed AUM | 12,884.83 | 16,715.14 | 21,380.14 | 22,520.17 |
| On-book AUM (WFPL) | 2,037.44 | 3,932.98 | 5,571.30 | 5,657.46 |
| Off-book AUM (Platform Partners) | 10,847.39 | 12,782.16 | 15,808.84 | 16,862.71 |
| AUM Growth (YoY) | N.A. | 29.73% | 27.91% | 27.18%* |
*Q1 FY27 figure is YoY growth vs. Q1 FY26 (June 2025 Managed AUM of ₹17,707.84 Cr).
The On-book share of AUM has been rising steadily — from ~15.8% of Managed AUM in FY2024 to ~25.1% by Q1 FY27 — indicating a gradual shift of mix toward WFPL's own balance sheet, which carries higher revenue (net interest margin) but also full credit risk, versus the fee-only, DLG-capped Platform Partner channel.
User cohort quality and stickiness
Repeat AUM (second-and-subsequent-loan borrowers as a % of Managed AUM) rose from 42.08% (FY2024) to 52.90% (FY2025) to 60.86% (FY2026), and further to 62.70% as of June 30, 2026 — indicating deepening engagement and lower incremental acquisition cost per rupee of AUM over time.
Monetized Users as a % of Registered Users improved from 5.55% (FY2024) to 8.48% (Q1 FY27).
User profile: average monthly income of ₹46,517.55, average age of 32 years, with 79.54% of Monetized Users based in Tier 2 and beyond cities as of June 30, 2026.
4. Key Business Strengths
- Large, sticky, flywheel-driven user base: 140.28 million Registered Users as of June 30, 2026, growing at a 26.92% CAGR (FY24–FY26), with growing user engagement compounding into higher monetization and repeat borrowing over time.
- Data-driven underwriting at scale: In-house AI/ML models trained on over 1,00,000 data variables support granular risk stratification; annualized loss rates on facilitated loans declined from 7.93% (FY2024) to 6.95% (FY2026) and further to 6.90% in Q1 FY27, evidencing improving portfolio quality even as volumes scale.
- Technology-led, asset-light operating leverage: A fully digital, branch-less model (over 50% of the workforce in technology/data roles) has driven Operating Expenses as a % of Total Income down from 56.42% (FY2024) to 34.84% (FY2026).
- Capital-light, diversified funding model: A 48-partner Financial Partner network — spanning banks and NBFCs — allows disbursal growth without proportionate balance-sheet capital commitment; WFPL's own capital adequacy remained comfortably above regulatory minimums, with CRAR of 24.32% as of March 2026 (regulatory minimum: 15%).
- Proven, improving unit economics: Loan Margin expanded from 7.48% (FY2024) to 8.55% (FY2026); Operating Profit nearly doubled over the same period (₹302.63 Cr → ₹790.02 Cr), evidencing a business model with genuine operating leverage as scale increases.
- Experienced, long-tenured leadership: Key Managerial and Senior Management Personnel have been associated with the Company for an average of ~7 years, spanning its growth from a personal-finance app to a multi-product credit platform.
5. Future Growth Strategy
Based on disclosures in the "Objects of the Offer" and business-model sections of the RHP, the Company's forward strategy centers on:
- Scaling default loss guarantee (DLG) capacity: ₹325.00 Cr of Net Proceeds is earmarked to fund growth in loan disbursals under DLG arrangements with Financial Partners — directly funding the Company's core Platform Partner lending channel.
- Strengthening the on-balance-sheet lending engine: ₹250.00 Cr of Net Proceeds is earmarked for capital infusion into WFPL, the Company's NBFC subsidiary, supporting continued growth of the higher-margin On-book AUM channel while maintaining regulatory capital-adequacy headroom.
- Deepening user monetization: Continued investment in the "flywheel" — converting the large Registered User base into Monetized Users and repeat borrowers — with Monetized-User conversion and Repeat AUM both showing consistent multi-year improvement.
- Cross-sell across the four product pillars: Leveraging the personal-loan relationship as an entry point to cross-sell the Transact, Invest and Protect categories (credit cards, insurance, digital gold, UPI, bill payments) launched since August 2024, to increase revenue per user and platform stickiness.
- Continued technology and AI/ML investment: Further build-out of underwriting and risk-segmentation models to sustain the declining loss-rate trend even as the loan book scales and product mix broadens.

Delete Comment?
Are you sure you want to delete this comment? This action cannot be undone.
Discussion
Join the discussion!
Log In to CommentNo comments yet. Be the first to share your thoughts!