SS Retail Limited
1. Overview
SS Retail Limited is a multi-brand retail chain for mobile phones, accessories and other electronic items, incorporated in 2016 and headquartered in Kolhapur, Maharashtra. The Company operates under the sector classification of organised consumer electronics and mobile phone retail, competing against both regional and national retail chains in India's fragmented mobile phone retail market.
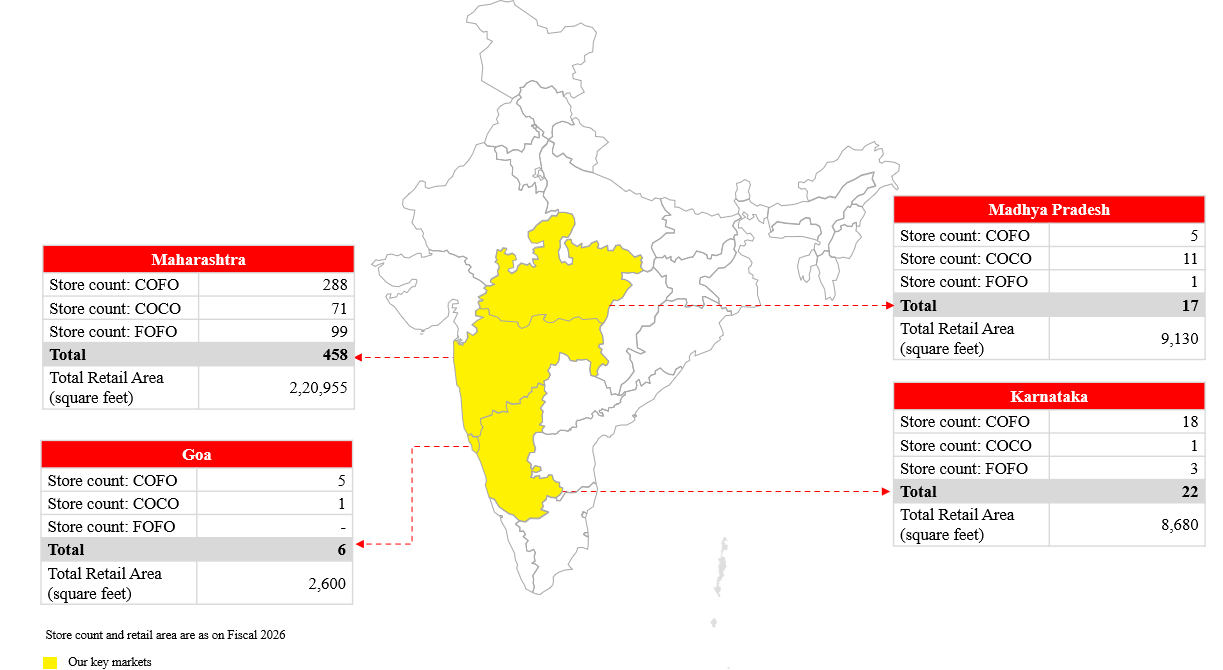
As of March 31, 2026, the Company operated 503 stores across five states — Maharashtra, Karnataka, Madhya Pradesh, Goa, and Gujarat (the last commenced in Fiscal 2027) — spanning 2,41,365 square feet of retail space across 215 cities. Of these, 458 stores (91.05% of the network) are concentrated in Maharashtra, where the Company holds the position of the largest mobile phone retail chain, per the Knowledge Company Report (an independent industry report commissioned by the Company). On a broader geographic basis, the Company is the largest mobile phone retail chain in West India (Gujarat, Maharashtra, Goa, Madhya Pradesh, Dadra & Nagar Haveli and Daman & Diu) and the 3rd largest in India among its peers by store count.
The network has scaled rapidly — from 236 stores across 109 cities as of March 31, 2024 to 503 stores across 215 cities as of March 31, 2026, a CAGR of 45.99%, which the Knowledge Company Report identifies as the 2nd-highest store-count growth rate among peers, roughly 2.4x the peer average of 19.29% over the same period. Post period-end, the network has continued expanding to 536 stores (2,60,597 sq. ft.) as of July 31, 2026.
2. Business Model and Revenue Streams
Store Operating Models
The Company runs three distinct store operating models, each with a different capital and revenue-sharing structure:
COCO (Company Owned, Company Operated): Company leases/owns and operates the store directly, bearing full Fit-Out capital expenditure.
COFO (Company Owned, Franchisee Operated): Company leases the premises; a local franchisee partner operates the store and earns a performance-linked commission upon hitting monthly revenue/profitability targets. The Company bears only partial Fit-Out capex.
FOFO (Franchisee Owned, Franchisee Operated): Franchisee partner leases and operates the store; the Company earns revenue via a fixed margin on inventory cost, while the franchisee bears store-level opex and retains residual profit. Inventory ownership remains with the Company across all three models.
The Company is franchise-led: as of March 31, 2026, COFO accounted for 62.82% and FOFO for 20.48% of the total 503-store count, with COCO at 16.70%. Revenue from the COFO channel grew at a 32.01% CAGR (FY2024–FY2026), while the smaller-base FOFO channel grew at 110.49% CAGR over the same period — reflecting an aggressive shift toward asset-light, franchise-driven expansion.
Revenue Bifurcation by Business Model (₹ Crore)
| Business Model | FY2026 Revenue | % of Revenue | FY2025 Revenue | % of Revenue | FY2024 Revenue | % of Revenue |
|---|---|---|---|---|---|---|
| COFO Model | ₹1,565.65 | 66.59% | ₹1,158.90 | 72.53% | ₹898.40 | 74.45% |
| COCO Model | ₹500.74 | 21.30% | ₹281.39 | 17.61% | ₹232.65 | 19.28% |
| FOFO Model | ₹178.62 | 7.60% | ₹87.94 | 5.50% | ₹40.32 | 3.34% |
| Corporate Sales | ₹109.80 | 4.67% | ₹69.71 | 4.36% | ₹35.39 | 2.93% |
| Adjustments | (₹3.78) | (0.16) % | — | — | — | — |
| Total | ₹2,351.03 | 100.00% | ₹1,597.93 | 100.00% | ₹1,206.74 | 100.00% |
Geographic Concentration (₹ Cr)
| Geography | FY2026 | % | FY2025 | % | FY2024 | % |
|---|---|---|---|---|---|---|
| Maharashtra | ₹2,094.57 | 89.09% | ₹1,475.26 | 92.32% | ₹1,135.22 | 94.07% |
| Goa, Karnataka & Madhya Pradesh | ₹150.44 | 6.40% | ₹52.96 | 3.31% | ₹36.14 | 2.99% |
The Company's heavy revenue concentration in Maharashtra (89–94% across the three years) represents both a structural strength (deep regional density and brand recall) and a geographic concentration risk, which the Company is actively addressing through its stated expansion strategy into Karnataka, Madhya Pradesh, Goa, Gujarat and the newly identified adjacent geography of Chhattisgarh.
Vendor/Supplier Dependency
The Company sources through direct arrangements with mobile phone brands and their distributors/authorised dealers, without long-term or exclusive contracts. Purchases from its top 10 suppliers constituted 79.09%, 89.42% and 88.38% of total traded-goods purchases in Fiscal 2026, 2025 and 2024, respectively — indicating meaningful supplier concentration risk, though the direct-procurement model is cited as enabling better trade margins, priority access to new launches, and faster replenishment cycles.
3. Products and Service Portfolio
Core Product Categories
- Mobile Phones: The primary revenue driver, contributing ₹2,026.11 Crore (86.18%) of FY2026 revenue from operations. Retailed across multiple brands and price points; also sold on a B2B/wholesale basis ("Corporate Sales").
- Pre-Owned Smartphones: Retailed under the "Mobile Exchange Wala" brand (launched Fiscal 2023) as a shop-in-shop format; contributed ₹169.35 Crore (7.20%) of FY2026 revenue — the fastest-growing category, up from 4.27% of revenue in FY2024.
- Accessories: Audio (bluetooth speakers, soundbars), hearables (earbuds, neckbands, headphones), wearables (smartwatches), and others (power banks, cables, memory cards) — contributed ₹100.82 Crore (4.29%) of FY2026 revenue.
- Other Electronic Items: Televisions, laptops, and tablets — ₹32.62 Crore (1.39%) of FY2026 revenue.
- Ancillary Services: Mobile protection plans, anti-theft software, EMI/credit facilitation via in-store finance kiosks, and mobile recharge — ₹25.91 Crore (1.10%) of FY2026 revenue.
Store Format Mix (by Area)
| Format | Area Definition | FY2026 Count | FY2025 Count | FY2024 Count | CAGR |
|---|---|---|---|---|---|
| Large Format Stores | >800 sq. ft. | 49 | 34 | 19 | 60.59% |
| Medium Format Stores | 400–800 sq. ft. | 219 | 194 | 136 | 26.90% |
| Small Format Stores | <400 sq. ft. | 235 | 119 | 81 | 70.33% |
Brand Portfolio
The Company operates three proprietary brands:
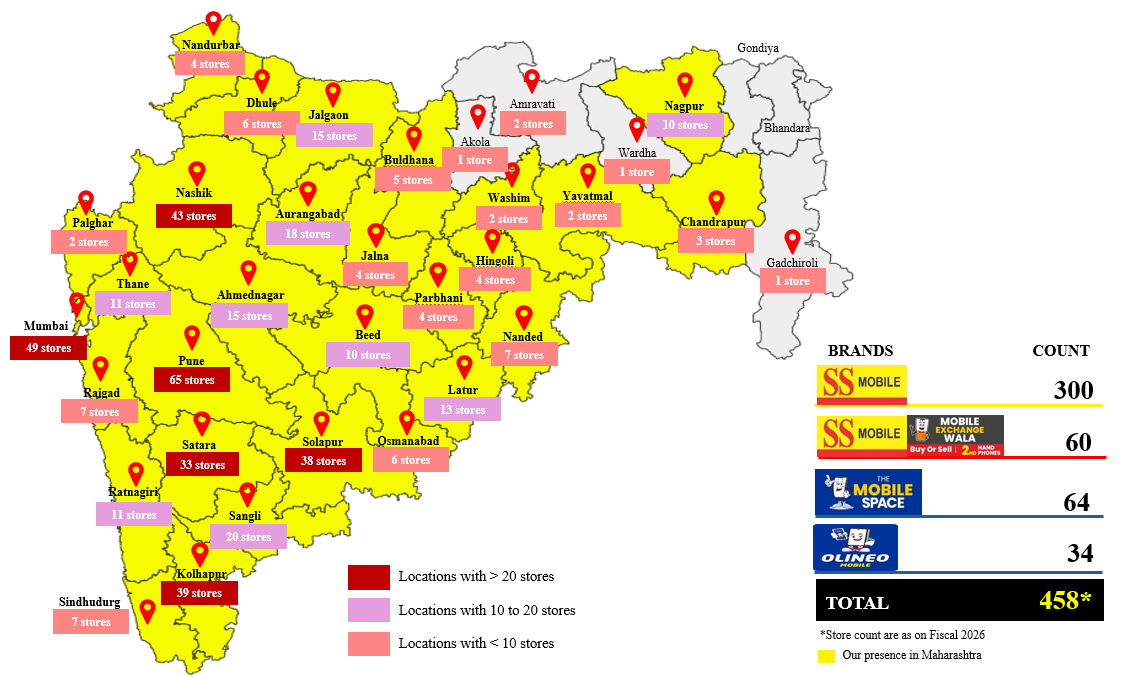
- SS Mobile — flagship brand (330 pure stores + 71 co-located "Mobile Exchange Wala" shop-in-shops = 401 stores)
- The Mobile Space — targeted at tier II/III+ cities via Medium/Small format stores (68 stores)
- Olineo (acquired, 51.04% stake, Fiscal 2026) — 34 stores, entirely FOFO-model, Maharashtra-based
Key Operating Metrics (Sector-Appropriate: Retail)
| KPI | FY2026 | FY2025 | FY2024 |
|---|---|---|---|
| Sales per Sq. Ft. | ₹1,46,347.03 | ₹1,20,188.73 | ₹1,15,340.99 |
| Same-Store Sales Growth (SSSG) | 11.17% | 13.43% | NA |
| Store Closure Rate | 5.37% | 3.46% | 2.12% |
| Gross Profit Margin | 12.18% | 12.09% | 10.67% |
| Inventory Turnover Ratio | 8.83x | 9.11x | 10.49x |
| Net Working Capital Days | 46 | 51 | 47 |
The Company's sales-per-sq.-ft. of ₹1,46,347 in Fiscal 2026 was the highest among peers, evidencing superior space productivity and store-format discipline.
4. Key Business Strengths
- Regional Market Leadership: Largest mobile phone retail chain in West India and Maharashtra, and 3rd largest in India among organised peers by store count, providing scale advantages in procurement and brand negotiation.
- Franchise-Led Asset-Light Expansion: 83.30% of stores operate under COFO/FOFO models, enabling faster store rollout with lower capital intensity than fully company-owned peers.
- Superior Growth Trajectory: Revenue CAGR of 39.58% and store-count CAGR of 45.99% (FY2024–FY2026) both rank as the highest among listed peers.
- Deep Tier II/III Penetration: 51.69% of stores are in tier III and beyond cities, positioning the Company ahead of the curve as the Knowledge Company Report identifies these as high-growth, under-penetrated markets.
- Diversified Format Strategy: A three-tier store format system (Large/Medium/Small) tailored to local market density, supporting disciplined, data-driven site selection with a low average store closure rate of 3.65% (FY2024–FY2026).
- Experienced Promoter-Led Leadership: Founder Siddharth Gunvant Shah brings 24+ years of mobile retail experience; supported by a management bench with 16+ years average tenure in the sector.
5. Future Growth Strategy
- Geographic Densification: Deepen penetration in the 458-store Maharashtra base while scaling newer geographies — Karnataka, Madhya Pradesh, Goa and Gujarat — and entering the newly identified adjacent market of Chhattisgarh (₹5,000 Cr mobile phone market per the Knowledge Company Report).
- Aggressive Store Rollout Funded by Net Proceeds: Plans to open 120 new stores each in Fiscal 2027 and Fiscal 2028 (57 and 58 of which are funded via the ₹12.45 Crore Net Proceeds allocation for Fit-Outs), predominantly under COFO/FOFO models.
- Working Capital Scaling: Deployment of ₹241.35 Crore of Net Proceeds toward incremental working capital, primarily inventory funding for new and existing stores.
- Accessory & High-Margin Mix Shift: Deliberate focus on growing the accessories and electronics mix, which carry structurally higher margins than mobile phone sales, aided by the Nexora-licensed accessory brand launched in Fiscal 2026.
- Inorganic Growth: Continued evaluation of bolt-on acquisitions, following the FY2026 acquisition of a 51.04% stake in Olineo (34 FOFO stores).
- Omnichannel Expansion: Evaluating an e-commerce (online-to-offline) platform leveraging the existing store network for last-mile fulfillment.
- Customer Retention Infrastructure: Roll-out of a loyalty-points programme (via EasyRewardz partnership) to drive repeat purchase and cross-sell of accessories.


Delete Comment?
Are you sure you want to delete this comment? This action cannot be undone.
Discussion
Join the discussion!
Log In to CommentNo comments yet. Be the first to share your thoughts!